Skip to content

GB · Buying real estate in Dubai

United Kingdom

Dubai buying guide · UK

A Dubai real estate brief for UK-connected buyers: compare the actual homes, net income and exit before deciding where the next purchase belongs.

Read the guide
Country context
UK
Last reviewed
Sources
5
Real sunset photograph across Dubai Water Canal toward Downtown Dubai
Dubai

01 · Your plans

Compare the holding you have with the home you would buy.

The way you intend to use the real estate shapes the location, budget and timing of the purchase.

UK buyer context

What changes when your purchase crosses borders?

A UK-connected buyer may be choosing a home in Dubai, a second base or an income property instead of another UK purchase. Each is a different brief. For an investment, compare two real units over the same holding period: purchase and transfer costs, achievable rent, service charges, management, vacancy, financing and a realistic resale buyer. A London yield beside a Dubai headline yield is not a like-for-like decision.

If you already own a UK rental, model the existing tenancy and your exit as well as the next purchase. England's private-tenancy rules changed on 1 May 2026; those rules are not a reason to assume every UK asset should be sold. The useful question is what you would actually receive after costs and timing, and what a specific Dubai unit would need to earn to justify the move.

HMRC treats rental profits from property outside the UK as an overseas property business and keeps its profits and losses separate from a UK property business. UK tax residence and any foreign-income treatment are fact-specific. A UAE residence permit does not decide the UK Statutory Residence Test. Before reservation, ask a UK-qualified adviser to model the relevant tax years and the proposed owner while Raj checks the Dubai building, running costs and exit market.
Retain, replace or diversify are three different decisions

A British buyer keeping a UK rental and adding Dubai is increasing their total property exposure. Someone selling the rental to fund Dubai is changing the portfolio. Someone moving to Dubai needs a home. Put the intended decision at the top of the comparison; it determines which costs, dates and alternatives belong underneath.

For a rental comparison, use two identifiable homes and the same capital commitment. Include the UK property's actual tenancy, building charges, repair needs and sale timetable. The Dubai side needs the precise apartment, achievable rent, service charges, management, vacancy and entry and exit costs. Neither city's headline yield answers that comparison.

Count the cash between the two properties

A sale price is not immediately spendable capital. Begin with expected net sale proceeds after debt repayment and transaction costs. Put the UK sale date, bank transfer, Dubai deposit and final payment on one timeline. A gap can create temporary accommodation or bridging needs even when the eventual purchase budget looks comfortable.

Show the Dubai holding in AED and the result in GBP at stated conversion rates. Rental income received overseas and money ultimately spent in Britain can have different currency exposures. Keep a weaker sterling-exit case visible rather than hiding it inside a single return percentage.

A £600,000 sale does not create a £600,000 Dubai budget

Consider an illustrative UK sale at £600,000 with £250,000 of mortgage debt to repay and £15,000 of selling costs. That leaves £335,000, not £600,000. If this buyer retains an assumed £35,000 for tax, moving costs and contingency, £300,000 remains for conversion. The reserve is an input, not a calculation of anyone's tax bill; replace each figure with the actual redemption statement, costs and required retained cash.

At an illustrative 4.70 AED per GBP, £300,000 converts to AED 1,410,000. At 5.00 it converts to AED 1,500,000: an AED 90,000 difference from the same sterling amount before bank charges. These are comparison assumptions, not current exchange rates or a forecast. The bank's executable quote and costs determine what actually arrives.

The arriving AED balance must still cover the Dubai purchase costs, any immediate work and the cash you intend to retain locally. It is not automatically the asking-price budget. If financing is part of the plan, show its confirmed terms separately rather than using an expected mortgage to close a cash gap on paper.

A Dubai deadline can arrive before the UK sale money

Put the sale's expected completion, mortgage redemption, cleared sterling, currency conversion and cleared AED beside the Dubai reservation and instalment dates. A UK sale agreed today does not make the proceeds available today. If the Dubai payment falls first, the missing item is dated funding, not a higher estimated sale value.

For example, a contractual Dubai instalment due in November cannot be funded solely by UK proceeds expected in December. Identify cash already available for that November payment, or a different purchase timetable, before committing. Do not treat a proposed bridge, an unapproved mortgage or an anticipated sale date as cleared funds.

The tenancy affects what a sale timetable can assume. England's current guidance requires the applicable grounds and process when a landlord seeks possession, including where the landlord intends to sell. That England-only guidance is not a UK-wide possession timetable. Keep the actual tenancy and conveyancing dates in the funding plan, not a generic assumption that the home can be vacant on demand.

Official guidance

Keep UK residence and overseas rental reporting separate from the visa

HMRC's overseas-property guidance separates the profits and losses of an overseas property business from a UK property business. Its post-April-2025 foreign-income rules require the buyer's actual residence history and circumstances; a generic 'tax-free Dubai' description cannot establish the UK result.

The UK Statutory Residence Test applies to the relevant tax year. A UAE residence permit is an immigration document, not a substitute for that test. Keep the owner, travel pattern, UK ties and future rental income in the same adviser brief before selecting an ownership structure.

Official guidance
Keep the UK and Dubai comparison on the same basis
CompareUK holdingDubai holding
CapitalNet sale proceeds or all-in cost of the actual UK homeAll-in purchase cost of the named Dubai unit
Illustrative sale-funded cash£600,000 less £250,000 debt, £15,000 costs and an assumed £35,000 retained reserve = £300,000£300,000 at illustrative 4.70 / 5.00 AED per GBP = AED 1,410,000 / AED 1,500,000 before bank costs and Dubai purchase costs
Funding dateActual sale completion, debt repayment and cleared transferable moneyCleared AED available by each contractual payment date; a later expected UK sale is not present funding
Annual incomeAchievable rent less building, letting, maintenance and vacancy costsAchievable rent less service charges, management, maintenance and vacancy
Time before incomeExisting tenancy and actual possession or sale timetableCompleted and let, or delivery plus furnishing and letting time
ExitDebt, sale costs and the UK ownership/tax positionDebt, sale costs, buyer depth and GBP conversion assumptions

02 · Tax, funding and ownership

Questions to resolve before you buy.

Take these questions to the adviser handling your tax, legal or banking arrangements. The answers depend on where you live and how you fund and own the home.

  1. Q01

    What is the buyer's UK tax-residence position for the current and expected future tax years?

  2. Q02

    How should overseas property rent and a later disposal be reported under the buyer's current facts?

  3. Q03

    If the buyer owns a UK rental, how should UK and overseas property-business income and losses be kept separate?

  4. Q04

    If an English rental would be sold to fund Dubai, what are the actual tenancy, possession, sale-cost and timing constraints?

  5. Q05

    Do current foreign-income-and-gains rules or transitional provisions affect this buyer?

  6. Q06

    Would personal, joint, company or trust ownership change tax, reporting, finance or succession outcomes?

  7. Q07

    How should wills, inheritance exposure and powers of attorney be coordinated across the UK and UAE?

Moving to the UAE

Ownership and residency are separate steps.

Reviewed 12 September 2026. ICP's guide, updated 10 September, and Dubai Land Department's investor service both describe a ten-year property route from AED 2 million. ICP also describes approved-local-bank finance and an approved off-plan category; DLD asks for title and, where mortgaged, bank paid-amount evidence. A listed price does not establish the buyer's eligibility or replace the issuing authority's decision.

Who handles what

Real estate advice and specialist support.

Raj handles the UAE property and transaction decision. A UK-qualified tax adviser and solicitor determine residence, foreign-income, ownership, reporting and succession conclusions; UAE counsel handles local title and transaction documents.

03 · The purchase

Before you reserve a home.

Before any reservation

Purchase checklist

  1. 01

    Confirm who will own the property and why that ownership route fits the intended use.

  2. 02

    Document source of funds and the transfer path before paying a reservation amount.

  3. 03

    Ask home-jurisdiction counsel how ownership, rent, disposal and succession should be reported.

  4. 04

    Check the title, contract, payment schedule, service-charge evidence and exit restrictions for the exact property.

  5. 05

    Treat residency as a separate authority application, not a promised property feature.

How you hold the asset

Ownership options

  1. 01

    Personal ownership - model current UK reporting, disposal and succession consequences first.

  2. 02

    Joint ownership - document beneficial shares and obtain UK and UAE succession advice.

  3. 03

    Company or trust ownership - use only after advisers explain current tax, reporting and administration effects.

A familiar structure may still be wrong for the buyer, lender, property or succession plan. Qualified review is required.

04 · Further reading

Your questions and the sources behind this guide.

Open the original guidance for detail. Review dates show when each source was last checked, not when the underlying rules were introduced.

Primary and official sources

  1. 01

    UAE Federal Authority for Identity, Citizenship, Customs & Port Security

    Golden Residency - current eligibility categories

    Federal guide updated 10 September 2026: ten-year property-investor category, AED 2 million threshold, approved-local-bank finance and approved off-plan category. The authority determines an individual's application.
    Official source
  2. 02

    Dubai Land Department

    Golden Visa application - real-estate investor

    Dubai ten-year investor service with title-deed and, for mortgaged property, bank paid-amount and no-objection evidence.
    Official source
  3. 03

    HM Revenue & Customs

    Tax on overseas property income

    Official general guidance updated for the post-April-2025 regime. Individual treatment remains fact-specific.
    Official source
  4. 04

    HM Revenue & Customs

    Statutory Residence Test guidance

    Official residence guidance; a qualified adviser should apply it to the buyer's complete facts.
    Official source
  5. 05

    UK Ministry of Housing, Communities and Local Government

    Renters' Rights Act overview for tenants

    Official summary of England's private-tenancy changes from 1 May 2026; individual tenancy and sale timing depend on the facts.
    Official source

Questions this page can answer

01Does buying a Dubai property guarantee residency?

No. Property ownership may form part of an application route, but the competent authority decides whether the current value, ownership, finance and document requirements are met.

02Does a UAE residency permit settle home-country tax residence?

No. Immigration residence and tax residence are separate tests. A qualified adviser in every relevant jurisdiction should determine the buyer's position from current facts and rules.

03Can Raj choose a legal or tax structure for me?

Raj can make the property objective, funding path and transaction questions clear. Legal, tax, immigration and regulated financial conclusions stay with appropriately qualified professionals.

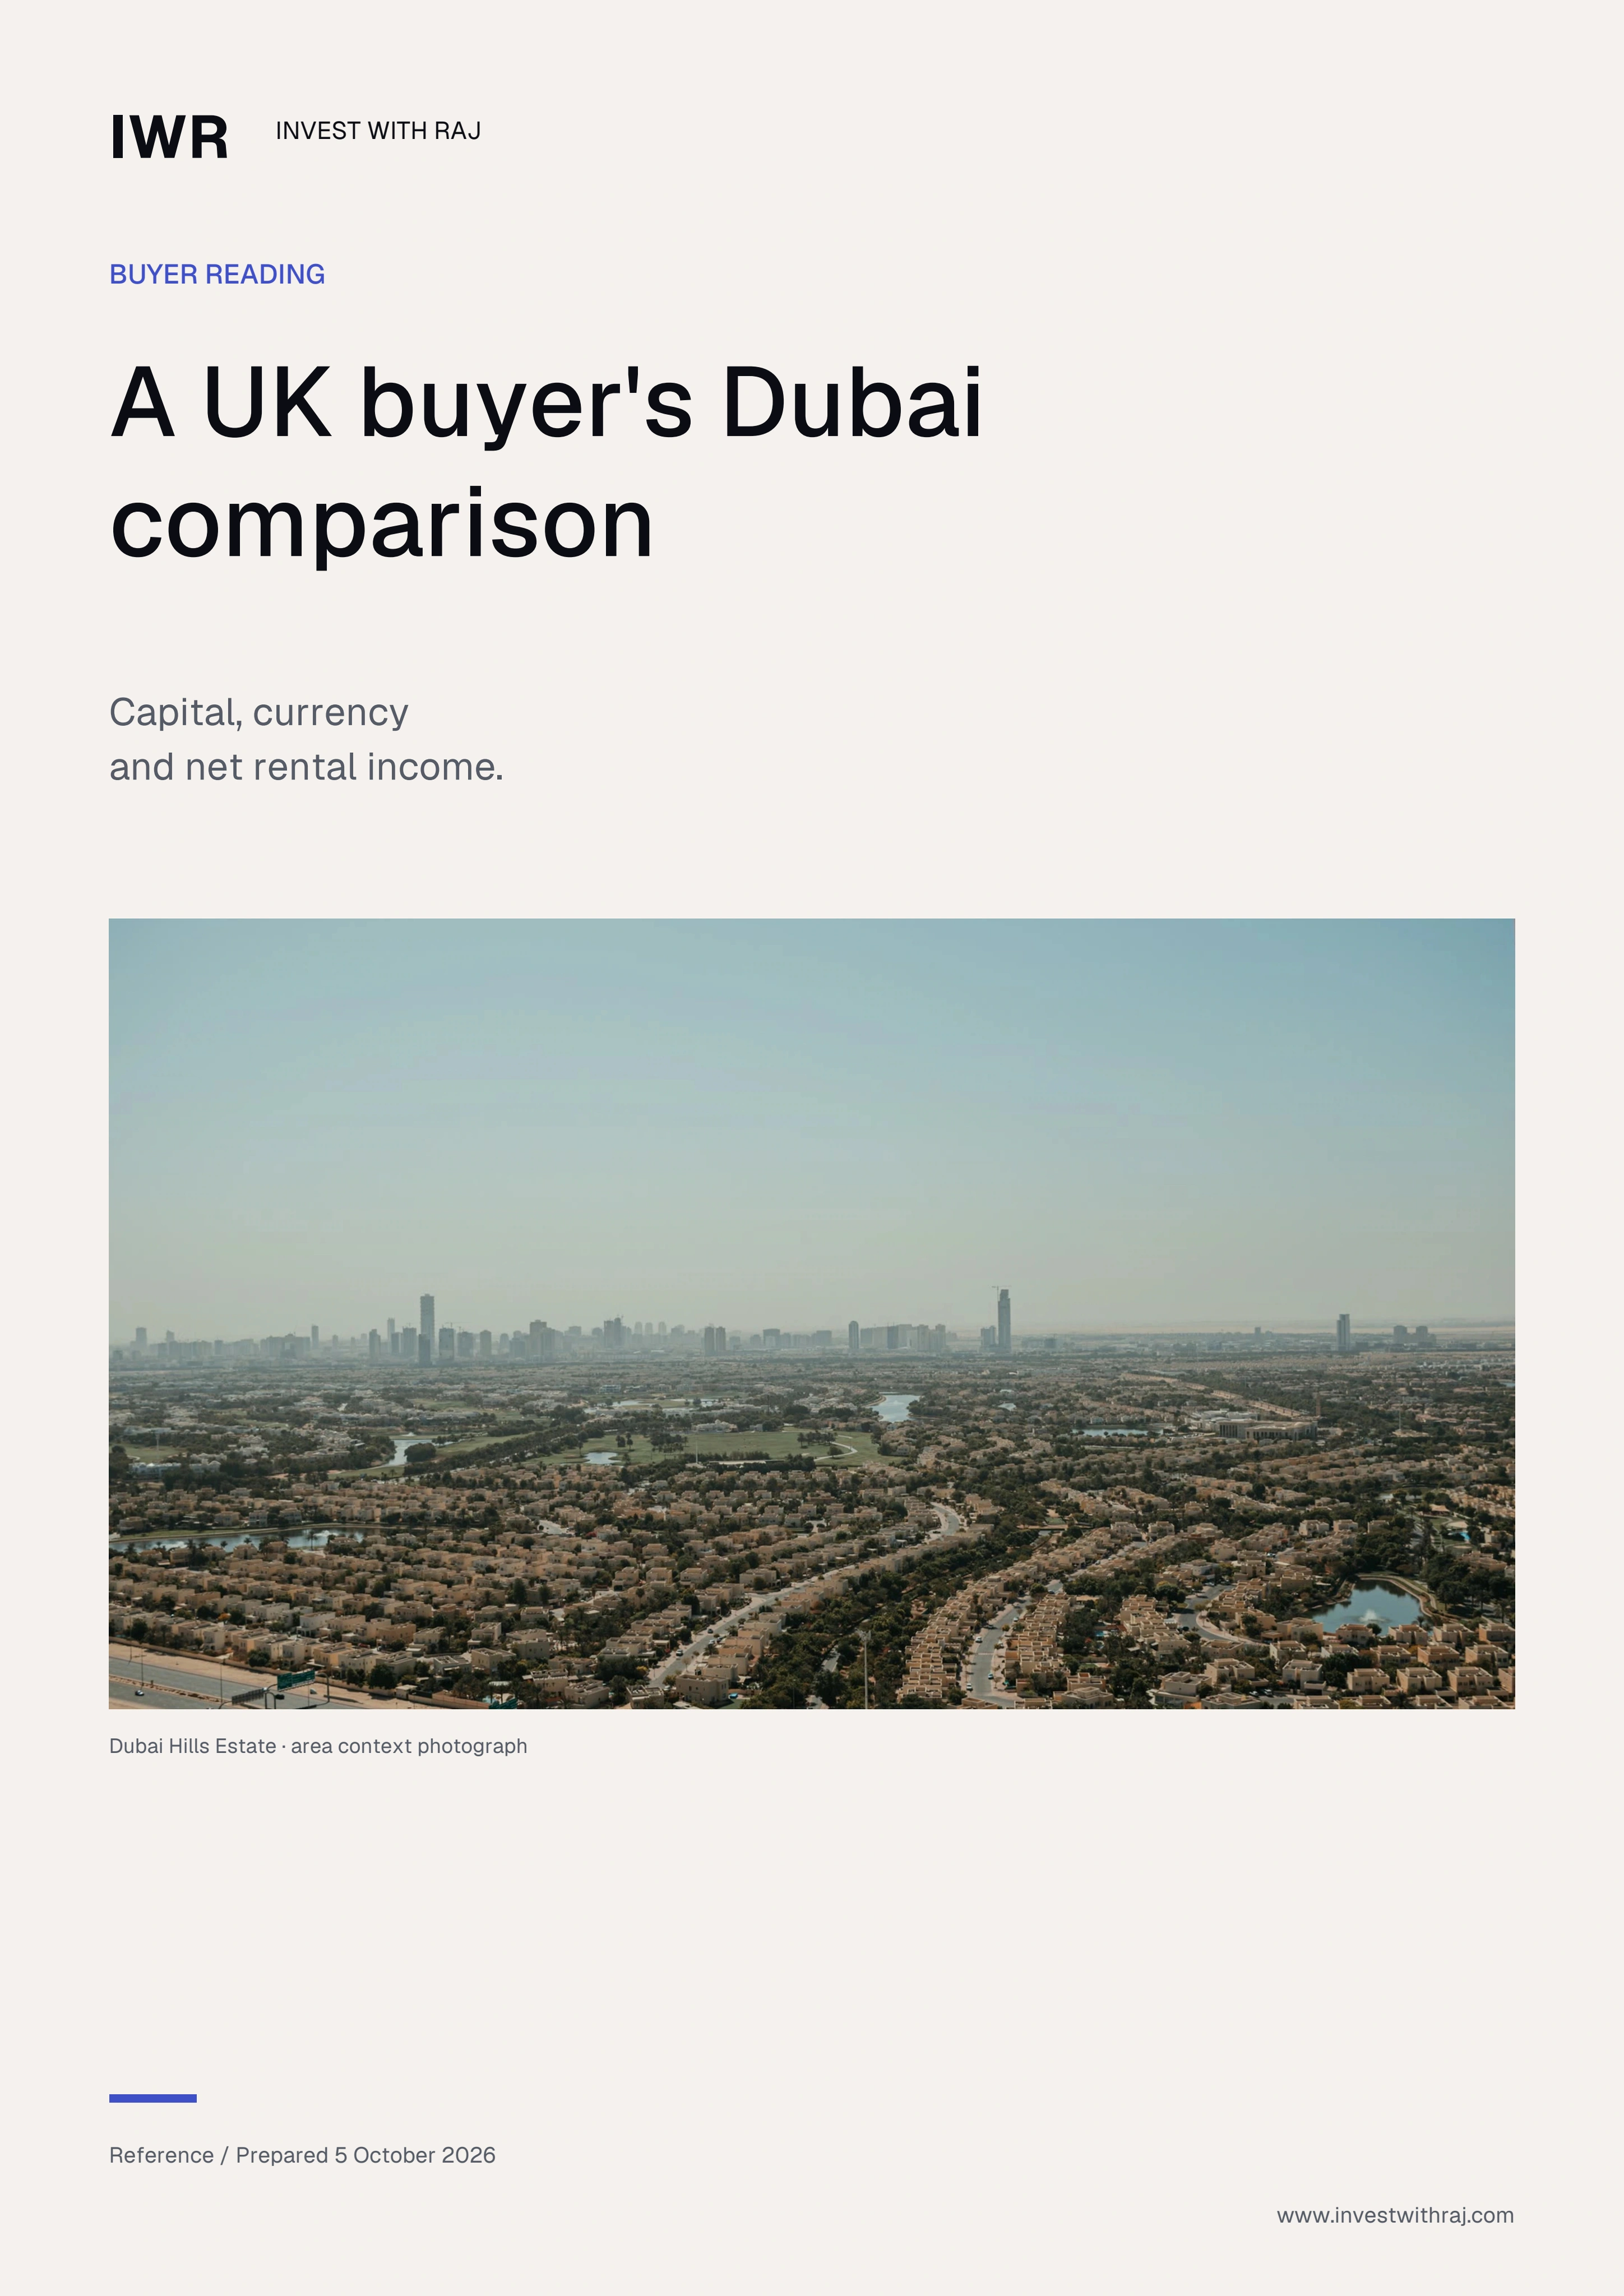
First page of A UK buyer's Dubai comparisonPreview the PDF

Take the reading with you

A UK buyer's Dubai comparison

Compare capital, net income, currency and the timing of a move from one holding to another. Includes sources and links to continue reading.

Download the reading PDF · 3 pages ↓
Raj Tomar, UAE real estate advisor
Raj Tomar · UAE real estate advisor

05 · Your next step

Let’s talk about your plans in Dubai.

Share where you live, what you want to buy and your timing. We can then discuss the areas, homes and research most relevant to you.

Start the private brief