Skip to content
Invest With RajIWR / Buyer field guide

Buyer field guide · 12 minute read

UAE Mortgages for Non-Residents

Read lending capacity, valuation, cash exposure and exit terms before choosing the property.

Read the guide
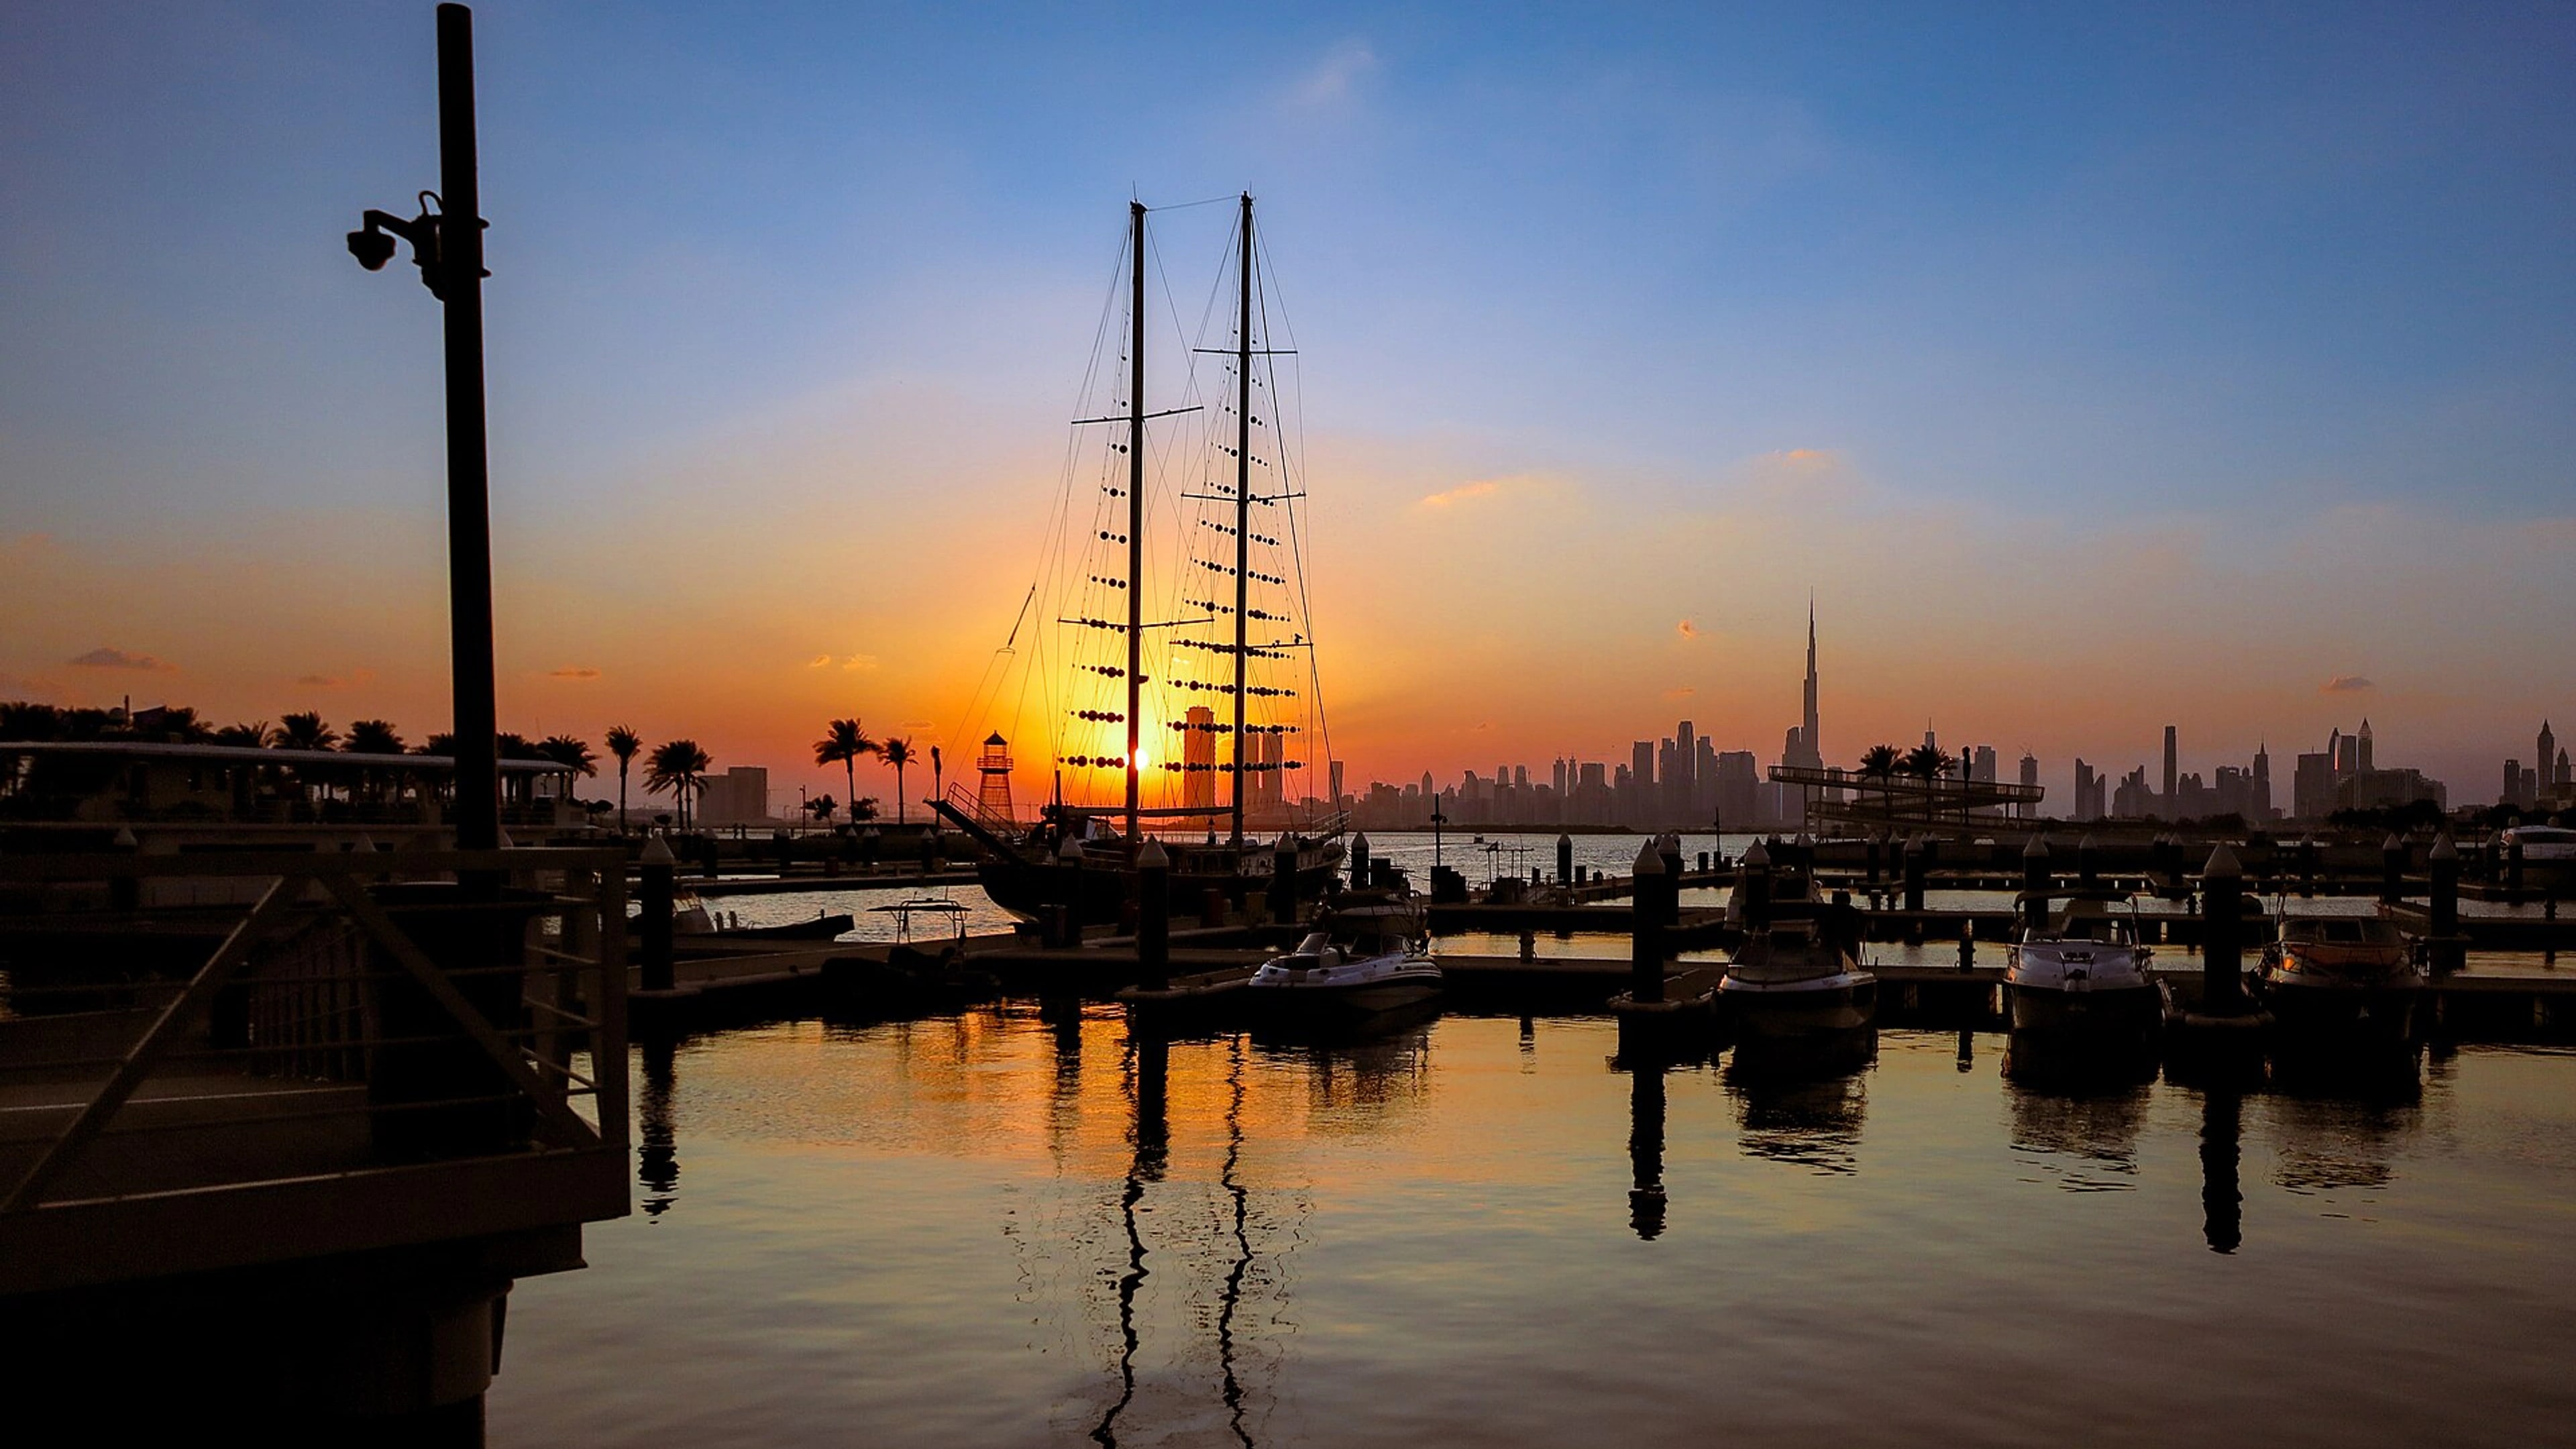
Real view of Dubai Creek Harbour
Real view of Dubai Creek HarbourDubai Creek Harbour photograph by Yousrafayed · Yousrafayed · CC BY-SA 4.0 · Cropped, resized and converted to WebP
Built for
International buyers considering UAE property finance
Format
Buyer field guide
Published
Last reviewed
Reviewed and accountable
Raj Tomar

What this guide is for

Build a finance brief that distinguishes regulatory ceilings, lender policy, applicant approval, property valuation and final drawdown.

Central Bank rules set a national framework, while lenders apply their own underwriting. Registration examples here are Dubai-specific; other emirates use their own land authorities and fees.

02 / The working guide

Read the checks in sequence.

Each chapter keeps its question beside the explanation and the authority record that supports it.

01

Decision check

Separate the four layers of a mortgage decision

First is the Central Bank framework, including maximum loan-to-value and affordability controls. Second is the lender's product and credit policy. Third is the applicant's documented income, liabilities, residency and profile. Fourth is the lender's valuation and acceptability of the specific property. Passing one layer does not guarantee the next.

Ask for written, dated terms and record what remains conditional. A pre-approval or indication can expire, assume information that later changes or exclude a property the lender will not finance. Build a purchase plan that remains viable if the advance is lower than hoped.
02

Decision check

Model the equity and all non-financed cash

The deposit is only one line. Include the gap between contract price and lender valuation, authority sale and mortgage registration, valuation, bank processing, insurance where required, trustee or conveyancing steps and a liquidity reserve. Dubai's current service records show its registration mechanics and fees; confirm them again for the live transaction.

Do not assume a personal loan or other borrowing can be used to create the required equity. The Central Bank framework expects the down payment to come from the borrower's own resources. Ask the lender how it will verify the source and seasoning of funds.

Real beach landscape on Saadiyat Island
Real beach landscape on Saadiyat IslandSaadiyat Beach photograph by Adman Payne · Adman Payne · CC BY-SA 4.0 · Cropped, resized and converted to WebP
03

Decision check

Read the whole instrument, not the advertised rate

Compare fixed-period length, reference rate and margin after reversion, payment frequency, processing, valuation, insurance, early settlement, overpayment and refinancing terms. Use the lender's formal key facts and disclosures, not a verbal summary. Consumer-protection standards require disclosures, but the buyer still has to compare them.

Test the payment at a higher rate and against a weaker income or rental period. For an investor, the debt should be tested within the asset's net operating case; for a home buyer, it should fit the household budget without requiring optimistic future income.

04

Decision check

Treat off-plan finance and completion valuation as separate risk

Many off-plan purchases are funded through developer instalments before a mortgage is arranged near completion, but structures vary. A future mortgage is not guaranteed merely because the buyer expects one. The lender will assess the borrower, property, developer and valuation under the policy that applies at the time.

Model delay, an earlier-than-expected demand for funds, a lower completion valuation and a changed lending market. Confirm whether the project and unit are acceptable to potential lenders before relying on debt as the handover solution.

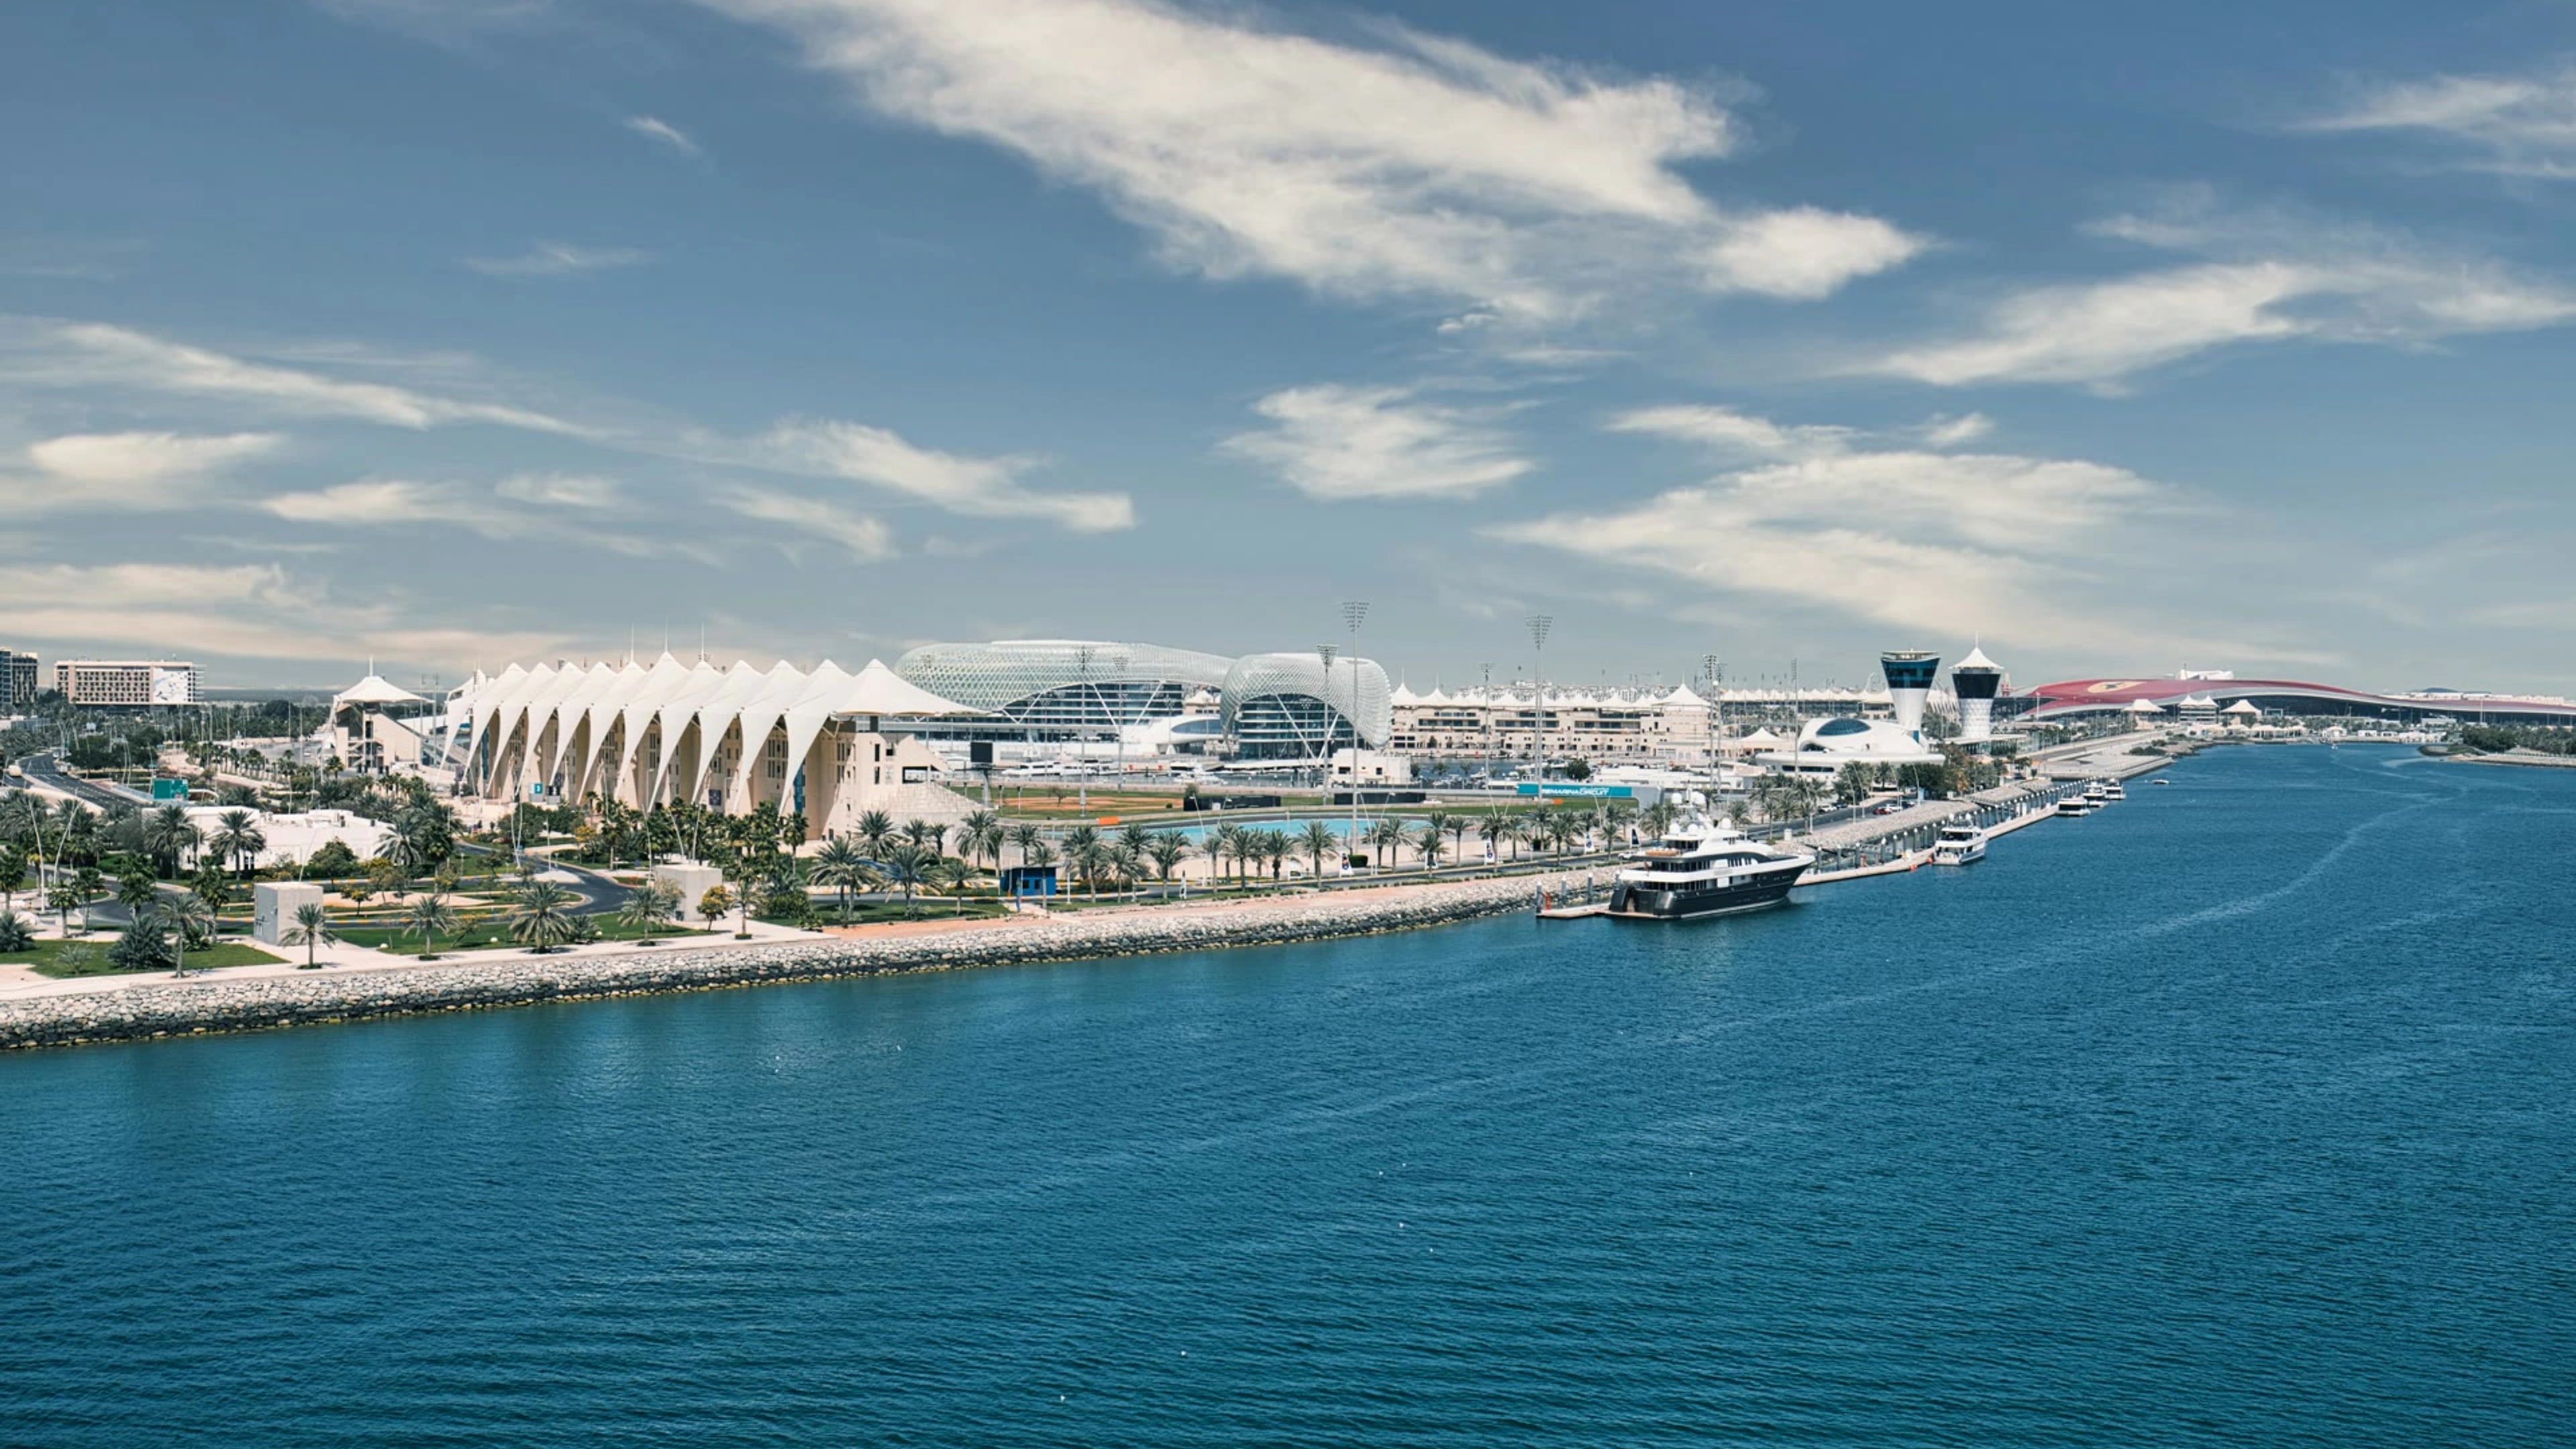
Real aerial urban context in Abu Dhabi
Real aerial urban context in Abu DhabiReal-source Abu Dhabi aerial photograph · Pexels License
05

Decision check

Borrow inside the limit, not automatically at it

A regulatory maximum and a lender approval are ceilings, not recommendations. Retain room for rate movement, maintenance, vacancy, life changes and currency exposure. If the mortgage works only under the best rental, rate and valuation assumptions, the financing is defining the plan rather than serving it.

Before reservation, write the approved limit, chosen limit, reserve, rate stress and exit route. Obtain regulated mortgage and financial advice for personal suitability. Raj's role is to connect the property decision to the finance case, not to replace a lender or financial adviser.

03 / Keep visible

The brief in five lines.

  1. 01

    A regulatory maximum is not an approval or a recommendation.

  2. 02

    Lender policy, applicant underwriting and property valuation are separate gates.

  3. 03

    Model the valuation gap and every non-financed cost.

  4. 04

    Compare reversion and exit terms as closely as the initial rate.

  5. 05

    Never rely on a future off-plan mortgage without a completion fallback.

Working file

Bring evidence, not memory.

  • 01

    Written lender indication with conditions and expiry

  • 02

    Applicant document and source-of-funds file

  • 03

    Cash map including valuation downside and fees

  • 04

    Rate, reversion, settlement and refinance comparison

  • 05

    Off-plan completion fallback or post-purchase liquidity reserve

Pressure-test

Know what this guide cannot decide.

Educational information only. It is not mortgage, credit, financial, legal, tax or investment advice and is not an offer of finance. Eligibility, rates, valuation and approval depend on the lender, applicant, property and live rules.

Return to the decision checks ↑
Evidence drawer4 dated authority records
  1. M1

    Central Bank of the UAE

    Regulations Regarding Mortgage LoansIn force; consolidated 8 April 2020; checked 30 July 2026

    National mortgage framework, LTV and affordability controls.

  2. M2

    Central Bank of the UAE

    Consumer Protection StandardsIssued 2021; checked 30 July 2026

    Disclosure and consumer-protection standards for licensed financial institutions.

  3. M3

    Dubai Land Department

    Mortgage registration applicationLive service record; checked 30 July 2026

    Dubai mortgage registration process, current documents and fees.

  4. M4

    Dubai Land Department

    Property Sale RegistrationLive service record; checked 30 July 2026

    Dubai sale registration mechanics and non-financed transaction costs.

A contextual working call

Test the property against your finance case

Share the decision, timing and part that does not yet reconcile. Raj will help frame the property question and identify where an authority record or regulated specialist is still required.