IWR MONTHLY / OCTOBER 2026
Abu Dhabi residential market
Capital is expanding. Delivery and concentration still matter.
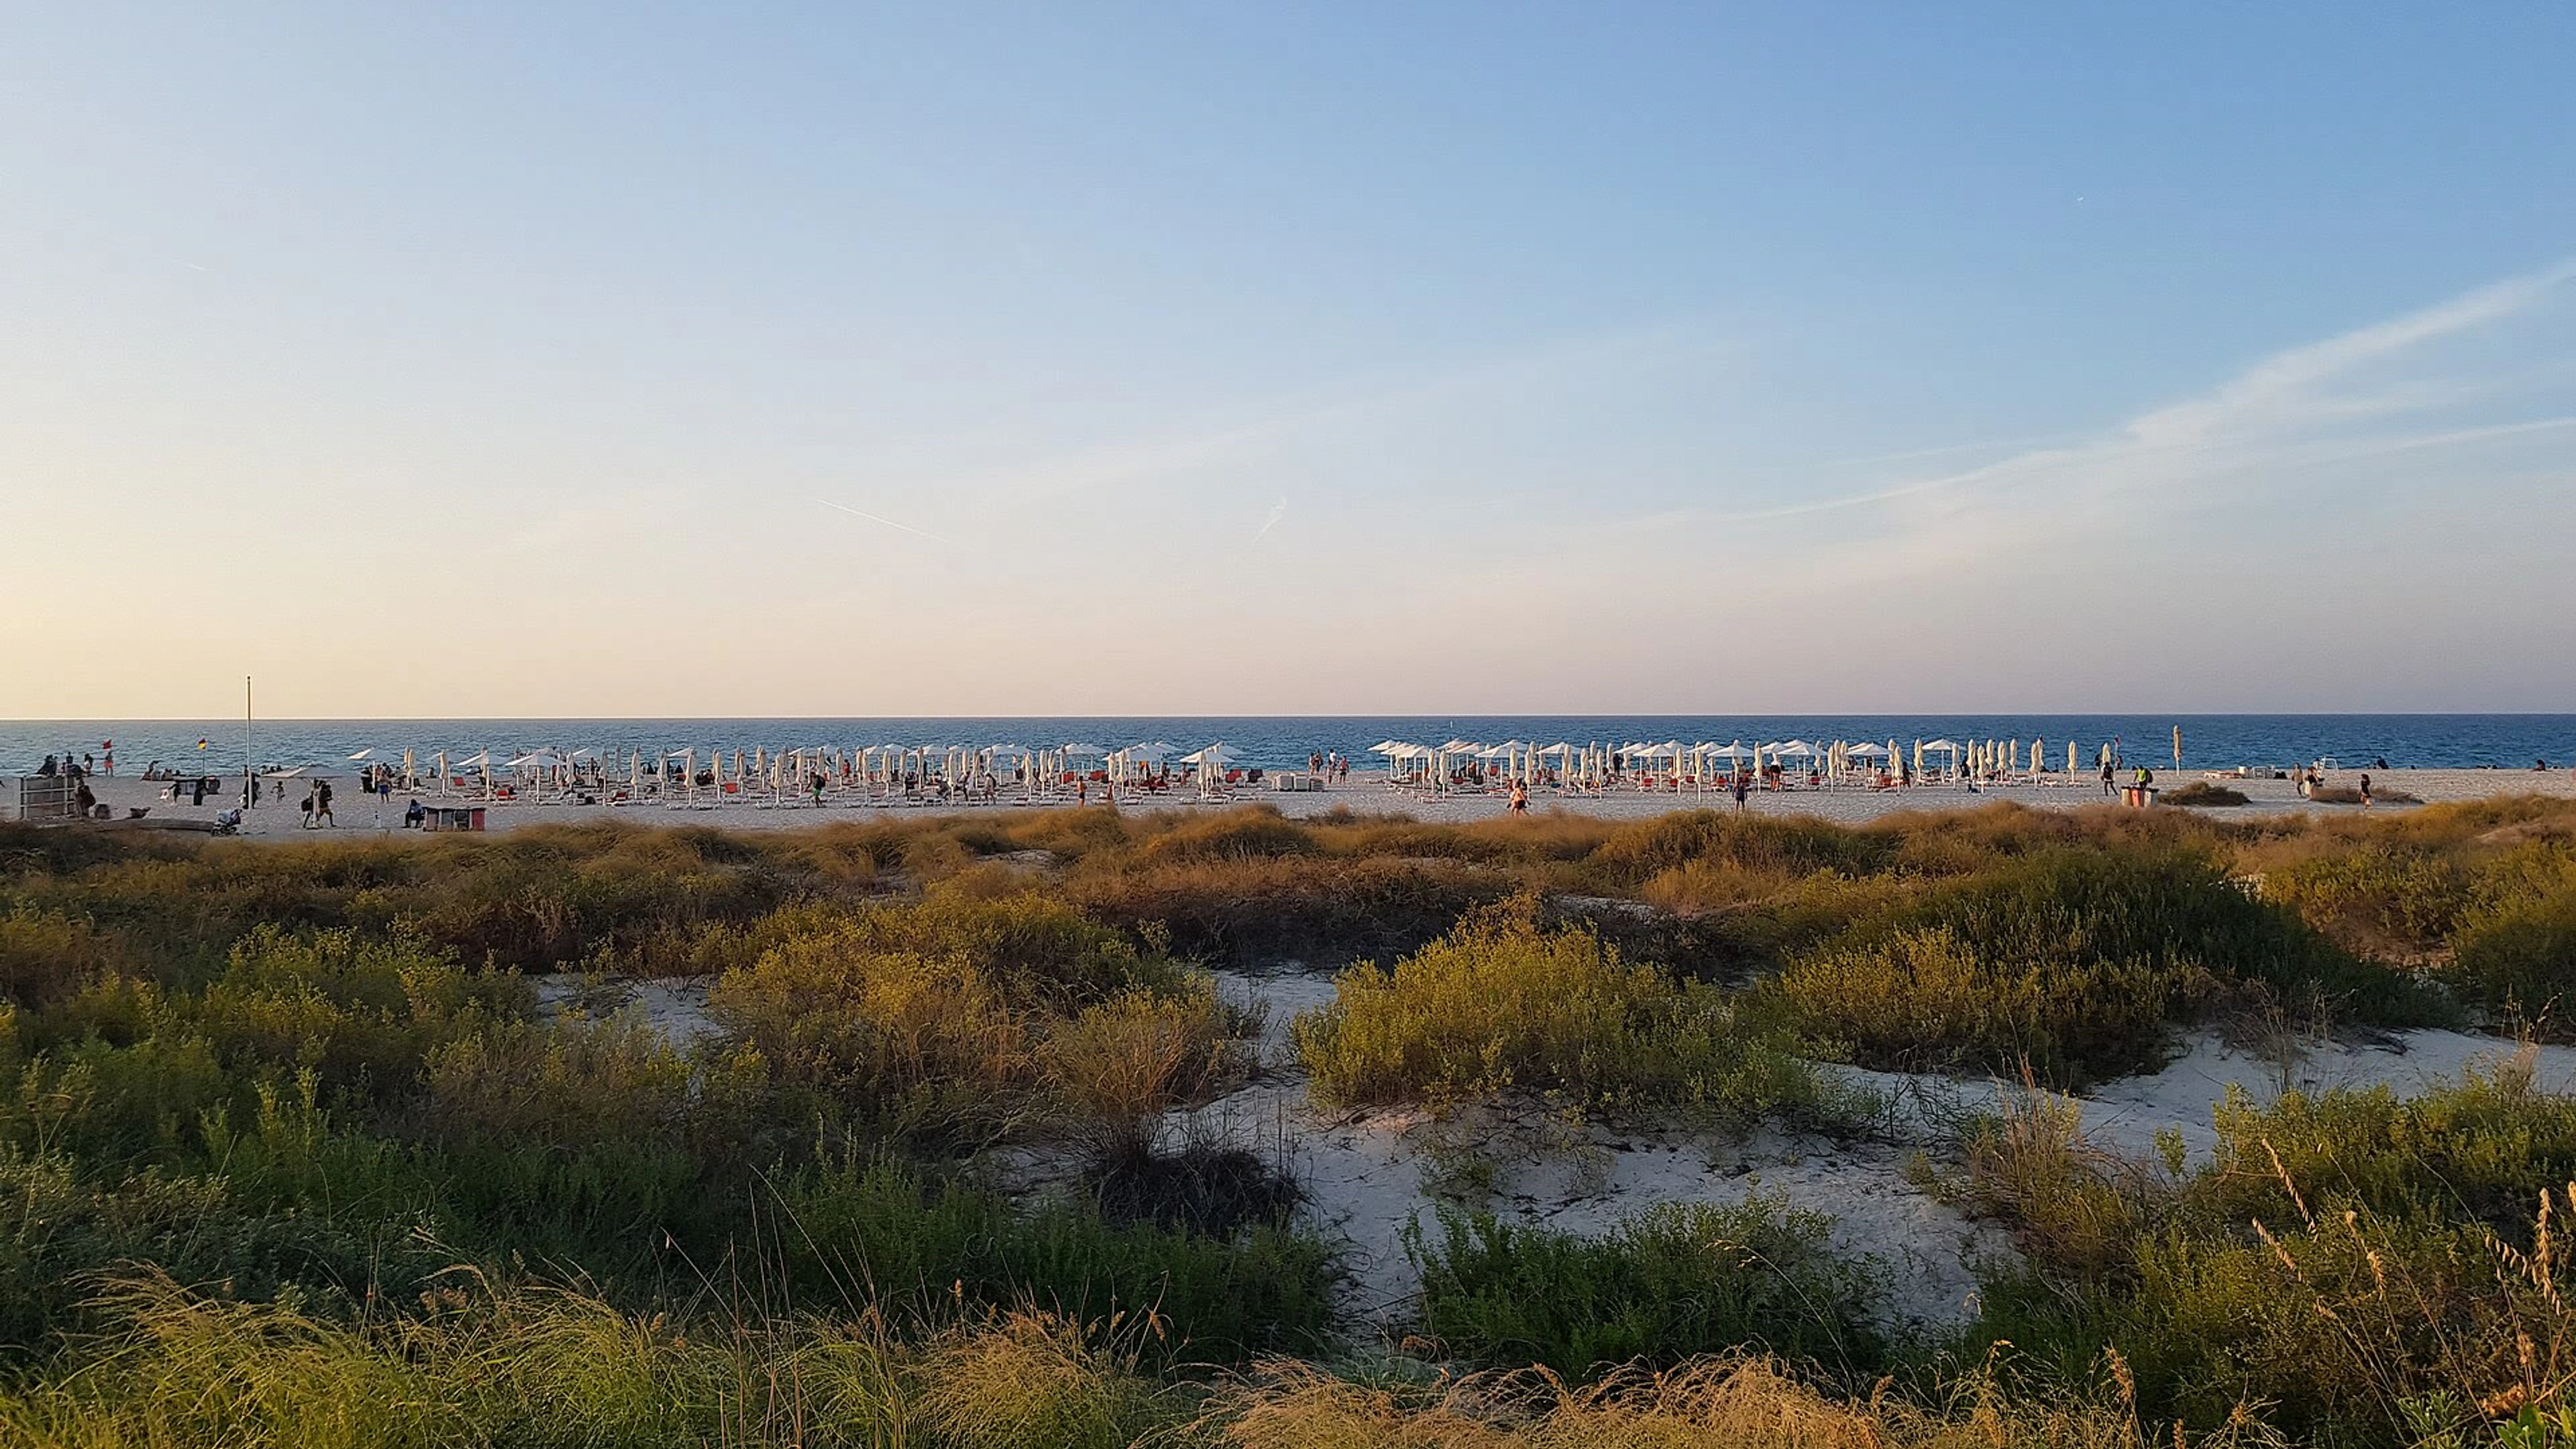
Saadiyat Island · Abu Dhabi location context · Evidence cut-off 13 October 2026H1 2026 · registered official evidence
Growth with a clear denominator
Residential sales and total real estate activity are different measures.
ADREC records AED 117 billion in total real estate transactions in H1 2026. Residential unit sales were AED 70.4 billion, against AED 25.3 billion a year earlier. The approximately 178% growth in residential sales value is not a 178% increase in the price of an individual property.
The total includes a wider transaction universe than residential purchases. Maintain the difference when comparing periods or cities. At a property level, repeat-sales evidence and matched local alternatives answer a different question from the amount of capital registered in a half-year.
| Measure | Value (AED billion) |
|---|---|
| H1 2025 | 25.3 |
| H1 2026 | 70.4 |
Most sales value is committed before completion
Off-plan concentration makes project oversight a central investment issue.
Off-plan homes accounted for 89% of residential sales value and 82% of deals in H1 2026. The value split was approximately AED 62.4 billion off-plan and AED 8.0 billion ready. These figures reveal where capital is committed, not where homes are already available to occupy.
Review the developer, registered project, escrow arrangements, payment milestones and delivered specification. In the ready segment, actual building condition, service costs and lease evidence can be inspected. Compare these commitments consistently rather than treating a payment plan as a price discount.
| Measure | Value (AED billion) |
|---|---|
| Ready | 8 |
| Off-plan | 62.4 |
The growth is not evenly distributed
A district comparison is more useful than a single emirate-wide conclusion.
Hudayriyat registered approximately AED 19 billion of residential sales value, followed by Saadiyat at AED 13.3 billion, the ADGM area at AED 10.5 billion and Yas at AED 7.3 billion. These are sales-value measures: they should not be described as rankings of rental yield, affordability or future appreciation.
Saadiyat’s cultural and coastal proposition, Yas’s leisure and residential mix, and Al Reem/Al Maryah’s relationship with ADGM create different housing decisions. The relevant district depends on occupation needs, property type, acquisition capital and the alternatives available to the expected tenant or future buyer.
| Measure | Value (AED billion) |
|---|---|
| Hudayriyat | 19 |
| Saadiyat | 13.3 |
| ADGM area | 10.5 |
| Yas | 7.3 |
Supply needs a regional reading
The emirate, Abu Dhabi Region and investment zones are not interchangeable.
The report identifies approximately 409,000 residential units across the emirate in H1 2026. Abu Dhabi Region contains approximately 324,000 units, including around 72,000 in investment zones. Those populations must remain separate in stock and occupancy comparisons.
Approximately 71,000 additional units are projected across the emirate by 2030. ADREC derives projections from registered projects, inspections and active building permits; they can change as the underlying records change. Location, infrastructure and delivery sequencing determine which homes become realistic alternatives for a particular buyer.
| Measure | Value (thousand units · current stock versus future additions) |
|---|---|
| Current emirate stock | 409 |
| Projected additional units | 71 |
Rent evidence belongs to the lease population
New leases, renewals and active contracts answer different questions.
ADREC records 233,000 active residential lease contracts across the emirate and AED 9.3 billion of lease value in H1 2026. An active-contract measure is not the number of homes newly let that month. New-lease movements should also be kept separate from renewal pricing.
For an income purchase, start with comparable registered leases for the exact property type and location, then deduct actual ownership, management and vacancy costs. Hotel or citywide rent indicators do not establish the net income of a selected apartment. Current lease rules and contract conditions require confirmation for the intended tenancy.
The next milestone is delivery, not another headline total
Watch what becomes usable and what the next official evidence actually measures.
Track registered completions, district-level leasing and the concentration of off-plan exposure. A cultural attraction or infrastructure announcement is a destination milestone; it is not proof of a particular home’s return. Existing and future facilities should be labelled separately.
The October edition uses the latest verified official half-year evidence. The date of this edition does not turn H1 observations into October sales or forecasts.
Sources and observation periods
October 2026 edition · published 13 October 2026. The observation period belongs to each metric, not the edition date. Figures are not forecasts or available-unit quotations.
- ADREC Abu Dhabi Real Estate Market Report H1 2026 · official full report ↗
- ADREC official market report archive ↗
Research and original analysis: Invest With Raj.
KEEP THE OCTOBER EDITION
Download the
Abu Dhabi report.
The interactive reading is open above. Share your details to receive access to this PDF edition.