01The investment case
Own the land, the outlook and the space.
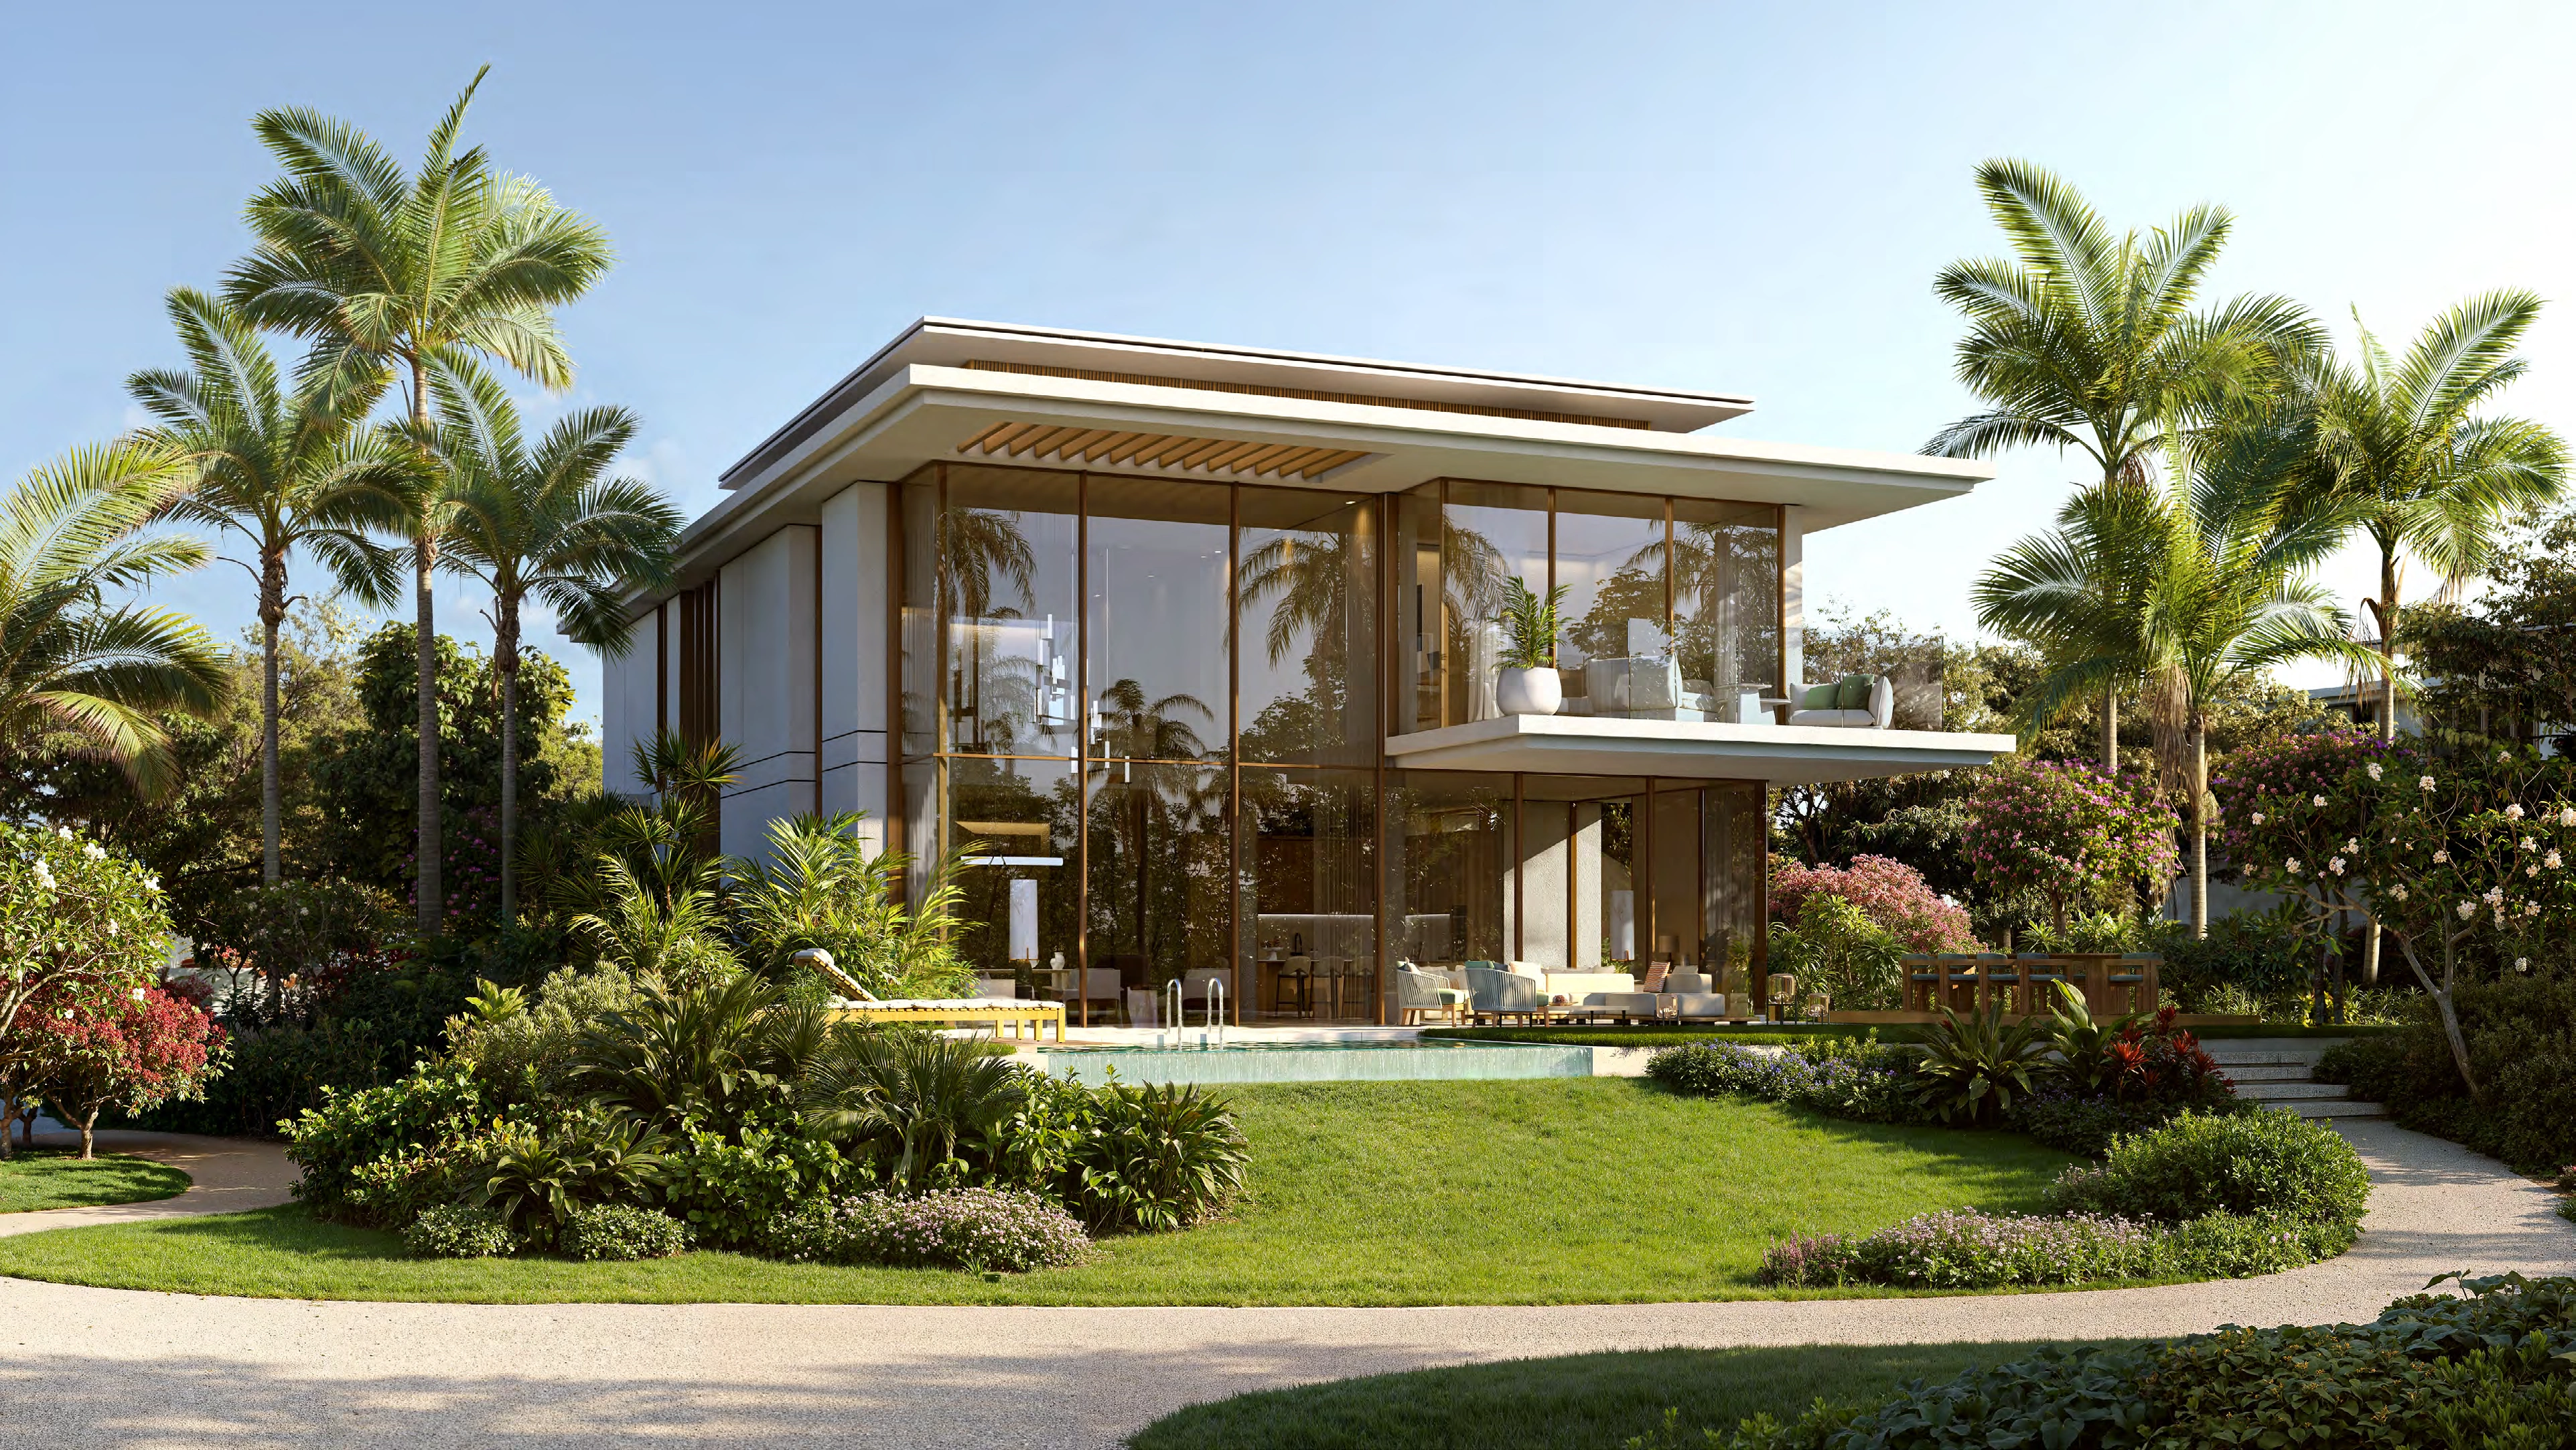
A villa purchase combines a home with private land. A plot adds control over the eventual home’s design. For a family buyer, garden space, privacy, access and the ability to adapt a residence can matter more than a building’s shared amenities. Those attributes create a distinct market from apartments.
Waterfront narrows the choice further: direct frontage cannot be added to an inland plot after purchase. Orientation, beach access, privacy and the width of the water outlook distinguish one coastal parcel from another. A sea glimpse and a private beach edge should not command the same treatment.
Island E brings this choice into a newly planned Nakheel community. The October release includes townhouses, attached villas, garden villas and land plots. The investment question is whether today’s entry price adequately rewards the buyer for waiting for that setting to become established.
Our view: the strongest case is the combination of usable land, a specific outlook and coordinated amenities. “Villa” or “island” alone is not enough; the individual position must carry the argument.
Sources for The investment case+
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
02The coastal comparison
Four peers. Four different reference points.
| Community | Best comparison | What distinguishes it |
|---|---|---|
| La Mer South | Custom villas / villa plots | Jumeirah coastal address; bespoke homes |
| Pearl Jumeirah | Villa land / completed mansions | Established island living and Nikki Beach setting |
| Jumeirah Bay / Bvlgari Island | Trophy land / custom villas | Branded destination and exceptional trophy positions |
| Palm Jumeirah | Completed beachfront villas | Mature hotels, services and resale market |
| Island E / Bay Estate | New homes / scheduled coastal plots | Coordinated new masterplan; earlier delivery stage |
La Mer South and Pearl Jumeirah are the closest custom-home and land comparables. Jumeirah Bay—often called Bvlgari Island—is the ultra-prime reference. Palm Jumeirah is the mature, larger-scale benchmark with the strongest widely published villa-price history.
These are coastal island communities with private residential components, not uniformly private islands. Hotels, public destinations, ownership formats and beach rights differ. Dubai Maritime City is useful waterfront context but is primarily a high-rise comparison; Solaya and Jumeirah Asora Bay apartments are not substitutes for villa land.
The geographic sequence runs from Palm Jumeirah in the southwest through Jumeirah Bay, La Mer and Pearl Jumeirah toward Dubai Islands in the northeast. Island E faces the Al Mamzar side of this northern coastal expansion.
Sources for The coastal comparison+
- Nakheel · Dubai Islands masterplan ↗
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
- Sotheby’s · La Mer South four-bedroom villa ↗
- Atara · Pearl Jumeirah H1 2026 villa sales ↗
03Five-year appreciation
The historical rise was substantial. Its scope matters.
Prime residential rise / five years
Equivalent annual compound growth
| Market / asset | Period | Verified observation |
|---|---|---|
| Dubai prime residential | Q4 2020–Q4 2025 | +194% · exact five-year broad benchmark |
| Palm Jumeirah villas | 2021 trough–Q1 2026 | Approximately 4× · ValuStrat narrative |
| Dubai prime villas | Jan 2021 base–Q1 2026 | Index 100 → 334.3 · +234.3% |
| La Mer South / Pearl villas & plots | Five-year request | Matched public series not established |
| Jumeirah Bay plots | 2021–2023 example | AED36.5M → 125M · see next chapter |
Knight Frank reports a 194% increase in Dubai prime residential values between Q4 2020 and Q4 2025. A starting index of 100 therefore becomes 294, equivalent to approximately 24.1% compound annual growth. This is a five-year prime-market benchmark, not a plot index.
ValuStrat’s Q1 2026 report describes Palm Jumeirah villas as approximately four times their 2021 trough value. Its prime-villa index stands at 334.3 against January 2021=100. These are valuation measures over roughly five years, with a different basket and endpoint from Knight Frank.
No consistent five-year, like-for-like plot and villa series was established for La Mer South, Pearl Jumeirah or Jumeirah Bay in the accessible evidence reviewed. Their high present prices and selected sales show positioning; they cannot establish that every asset tripled.
The current cycle also matters. ValuStrat reports Dubai villa values down 1.7% year-on-year in August 2026. Island E must therefore work on its entry price and delivery, rather than relying on the previous cycle to repeat.
Sources for Five-year appreciation+
04Bvlgari Island benchmark
Jumeirah Bay shows what exceptional land can command.
Registered plot sale / April 2023
Broker-reported villa sale / March 2025
| Asset / event | AED / USD | Evidence basis |
|---|---|---|
| 24,500 sq ft plot / 2021 purchase | 36.5M / 9.94M | DLD price reported by Bloomberg |
| Same plot / April 2023 resale | 125M / 34.04M | Knight Frank sale report |
| Gross change / approximately 2 years | +242.5% | Same plot; before costs |
| Separate tip villa / March 2025 sale | 330M / 89.86M | Dubai Sotheby’s reported sale |
A 24,500 sq ft Jumeirah Bay plot sold for AED125M in April 2023, approximately AED5,100 per plot sq ft. Knight Frank reported the sale; Bloomberg reporting, reproduced by The Business Times, puts its 2021 purchase at AED36.5M. The gross price increase was 242.5% over approximately two years.
The completed-home benchmark is different: Dubai Sotheby’s reported an AED330M custom-villa sale in March 2025 on a 26,895 sq ft tip plot. That is approximately US$89.86M. It demonstrates the price of an exceptional finished residence and position, not the value of an ordinary empty plot.
Island E’s scheduled waterfront plots average AED17.5M and its beachfront plots AED19M. The lower cheque is material for access to coastal land, but the parcels are smaller and the destination is less mature. It is not evidence of a like-for-like discount to a Bvlgari-address trophy home.
Island E offers earlier entry into a new community. Jumeirah Bay offers established status, destination branding and a track record at the very top of the market. Buyers are choosing between those benefits, rather than between interchangeable islands.
Sources for Bvlgari Island benchmark+
- Knight Frank · Destination Dubai 2025 ↗
- Bloomberg / The Business Times · Jumeirah Bay plot resale ↗
- Dubai Sotheby’s · AED330M Jumeirah Bay villa sale ↗
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
05La Mer South & Pearl Jumeirah
The completed-home price bracket is already high.
| Reference | AED / USD | Basis |
|---|---|---|
| La Mer South · 4BR villa | 60M / 16.34M | Current asking listing |
| Pearl Jumeirah · 7BR mansion | 50M / 13.61M | Search-listed ask; not a closed sale |
| Pearl Jumeirah · corner plot | 29.35M / 7.99M | Owner ask, updated 29 Sep 2026 |
| Bay Estate · garden villa | 10M / 2.72M | Official scheduled average |
| Bay Estate · waterfront plot | 17.5M / 4.77M | Official scheduled average |
| Bay Estate · beachfront plot | 19M / 5.17M | Official scheduled average |
A Sotheby’s La Mer South listing asks AED60M for a four-bedroom villa with 9,707 sq ft of interior space on a 7,226 sq ft plot. This is useful evidence of today’s marketed product, not a realised sale or a representative community median.
In Pearl Jumeirah, a Sotheby’s seven-bedroom mansion is search-listed at AED50M. Separately, developer Atara reports AED110M of aggregate villa sales in H1 2026. That supports an active luxury-home market without proving a particular per-villa return.
Land has its own comparison: Pearl Jumeirah owner listing PJ-012 asks AED29.35M for about 11,751 sq ft, approximately AED2,498 per plot sq ft. Its corner position is not established as direct beachfront. La Mer South’s AED29–30M plot examples are dated 2025 asking evidence; they are retained as historical context only.
The useful conclusion is a large difference in total entry cost. A finished custom mansion includes architecture, fit-out, landscaping and an existing address. Bay Estate land does not. Plot-to-plot and finished-home-to-finished-home selection must remain separate.
06Why Dubai Islands
A new coastal destination beside the existing city.
Islands in the wider masterplan
Total planned land area
Planned beaches
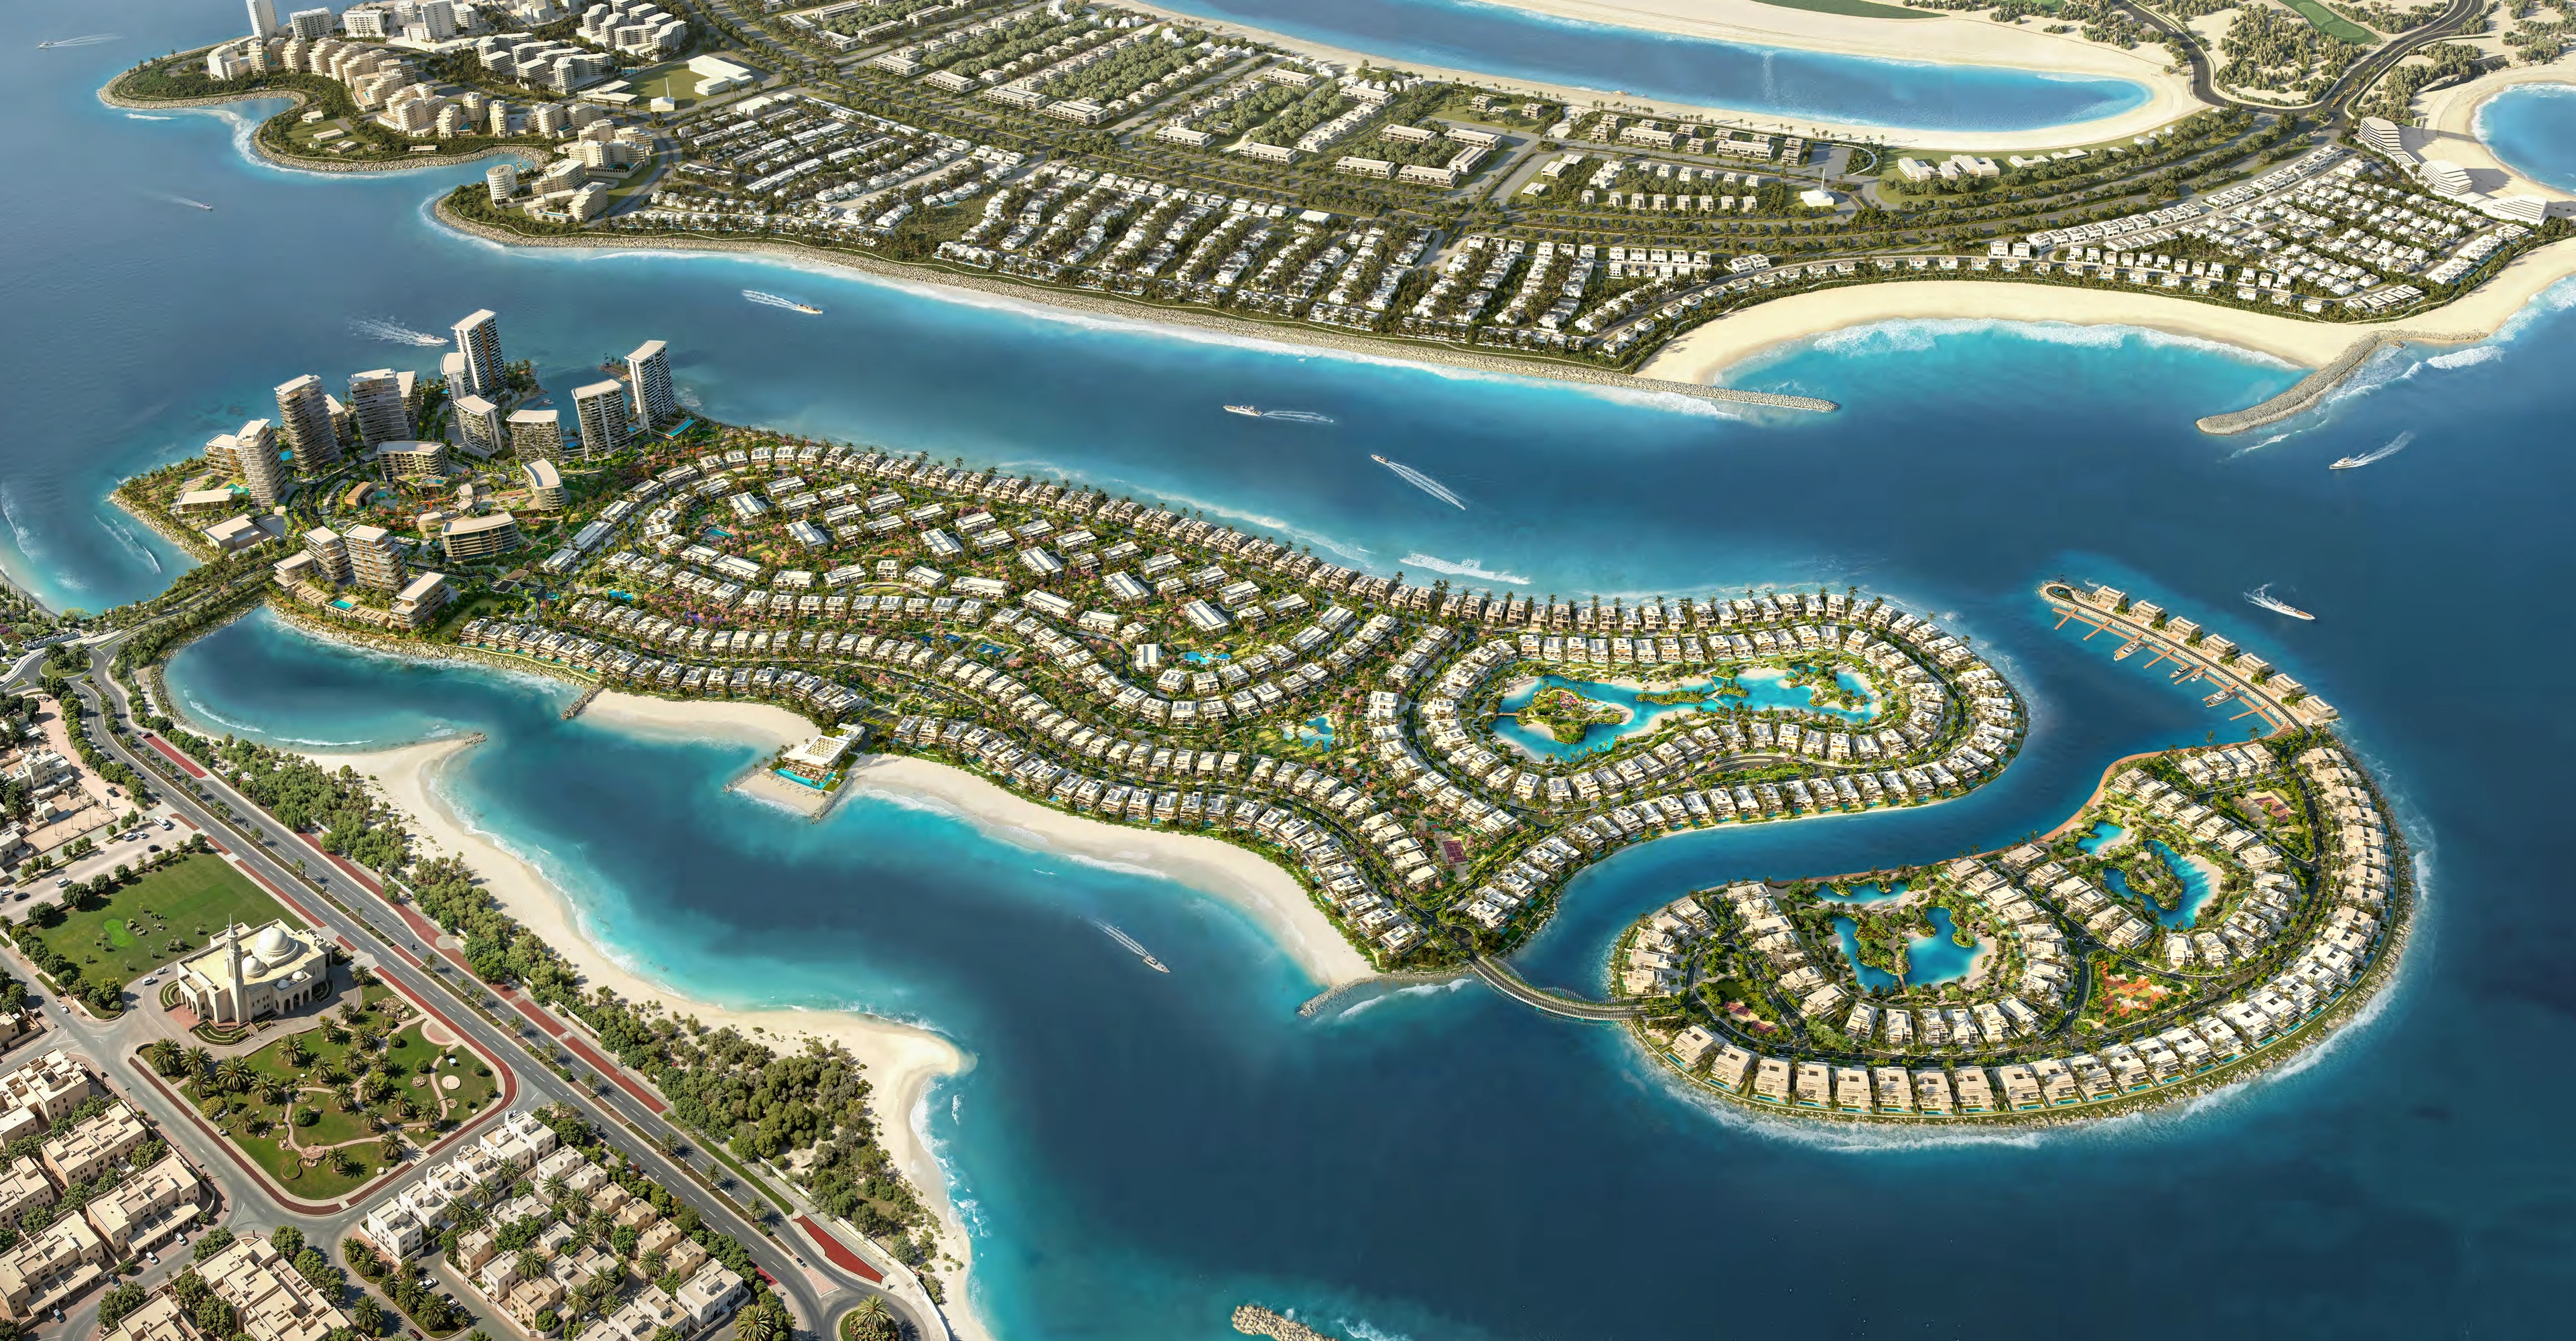
Nakheel’s masterplan spans five islands and 17 sq km, with more than 20 km of beaches and approximately 2 sq km of parks and open spaces. The scale provides room for several distinct residential and visitor markets, rather than one uniform investment product.
Its northern Dubai setting links the new coast to Deira and the Al Mamzar side of the city. For Island E, the supplied Bay Estate plan identifies a dedicated bridge approach from Al Khaleej / Al Mamzar. The precise access solution matters more than a generic drive-time promise.
The wider destination can support hospitality, services and residential demand as it develops. It also creates competing supply. Island E’s villa-and-plot offer should be assessed within that larger destination without assuming every new apartment or island shares its scarcity.
The five-year case is therefore about community delivery and better-established use, not completion of the entire archipelago. The official Bay Estate homes estimate points to January 2031; surrounding infrastructure and amenities follow their own sequence.
Sources for Why Dubai Islands+
- Nakheel · Dubai Islands masterplan ↗
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
07Why Island E
A distinctive residential setting within the larger destination.
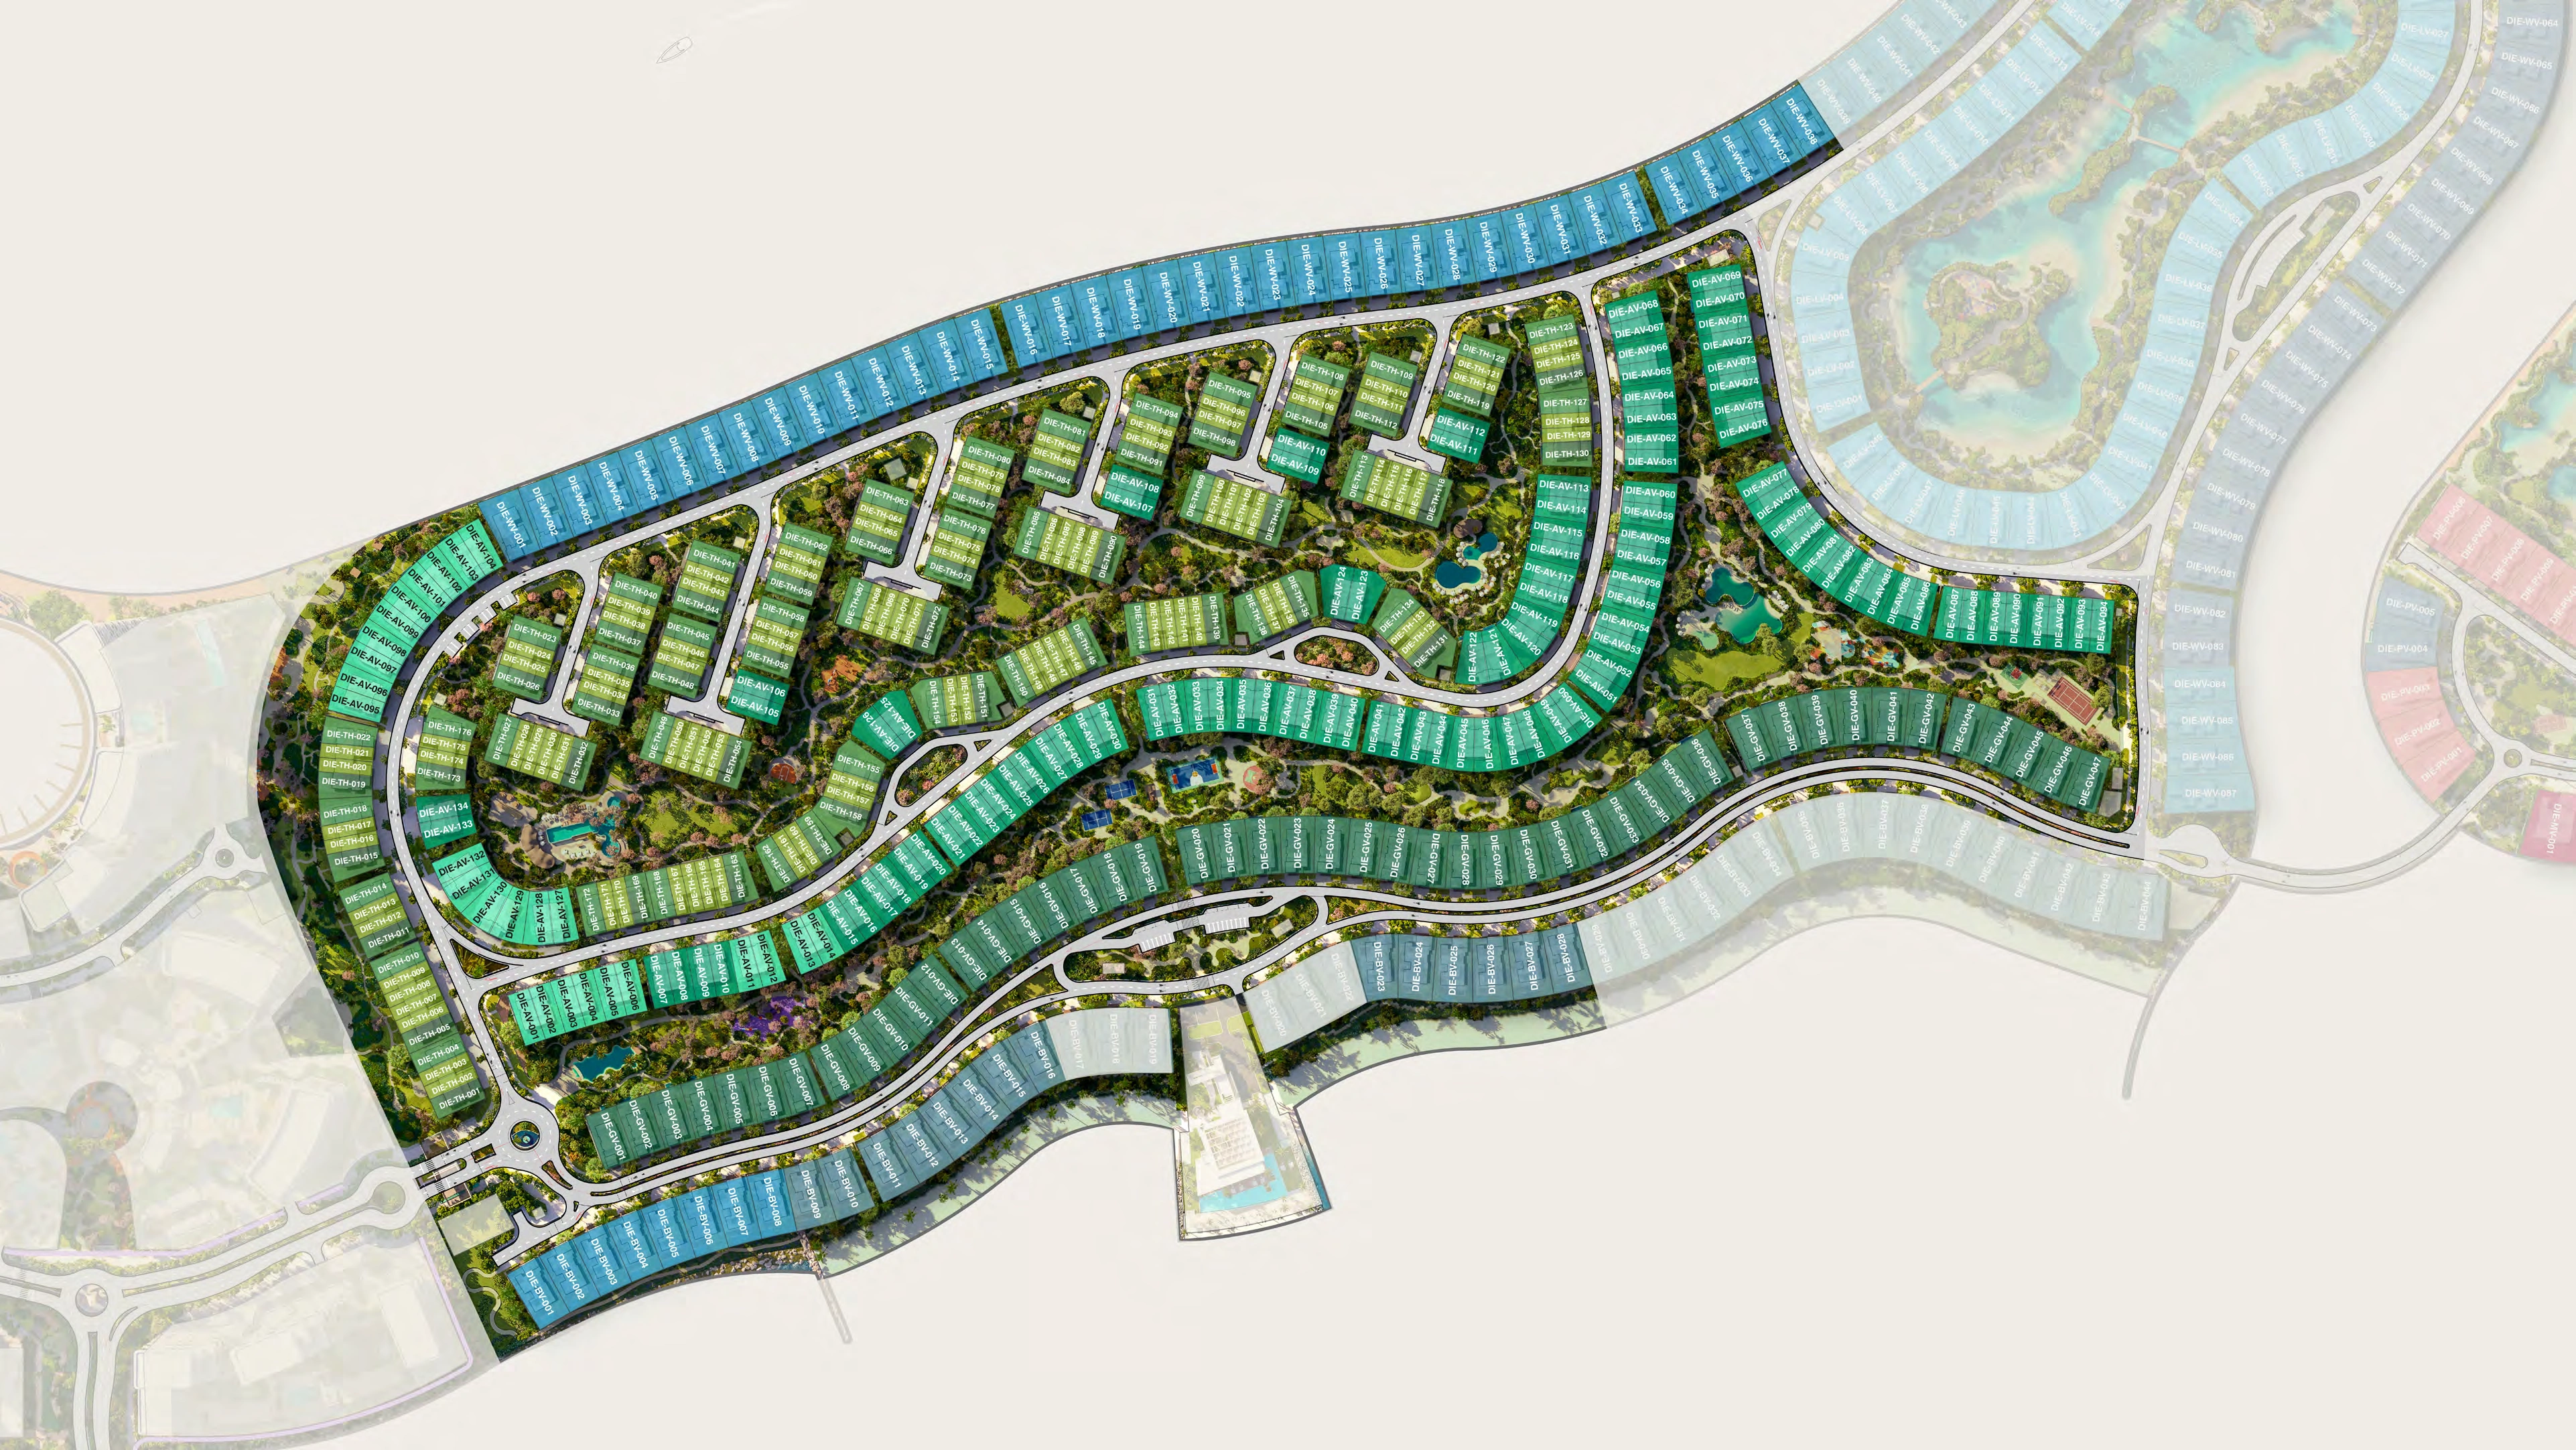
The official plan combines Cala, Verda and Agora districts with more than 30% open space, two swimmable lagoons, a beach club, two pool clubhouses, parks and marina berths. A dedicated approach gives the island a clearer residential identity within Dubai Islands.
The current schedule contains 357 homes and 60 coastal plots. This is the supplied release schedule, not a count of all future development on Island E. Fourplex and sixplex townhouse plans both appear in the official material.
Across the water, Al Mamzar’s AED500M public beach transformation adds a meaningful nearby public-realm investment. It strengthens the setting; it is not a private amenity owned by Bay Estate residents.
The strongest positions combine privacy, a useful garden or building envelope and an enduring outlook. Waterfront, beachfront, garden and internal positions should be priced separately. The combination of coastal plots, planned lagoons and substantial open space gives Island E a distinct residential proposition.
Sources for Why Island E+
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
- Dubai Media Office · Al Mamzar beaches development ↗
08The offering
Price, land and internal space—shown separately.
| Product | Count | AED / USD | Plot ft² | NSA / GFA ft² |
|---|---|---|---|---|
| 3BR Townhouse | 98 | 5.9M / 1.61M | 2,400 | 3,100 NSA |
| 4BR Townhouse | 78 | 6.9M / 1.88M | 3,900 | 3,500 NSA |
| 4BR Attached Villa | 66 | 7.2M / 1.96M | 4,100 | 3,700 NSA |
| 4BR Plus Attached Villa | 68 | 8.9M / 2.42M | 4,100 | 5,300 NSA |
| 4BR Garden Villa | 47 | 10M / 2.72M | 6,500 | 5,200 NSA |
| Waterfront Plot | 46 | 17.5M / 4.77M | 8,000 | 7,800 GFA |
| Beach Plot | 14 | 19M / 5.17M | 8,100 | 7,800 GFA |
The October briefing quotes average prices and average areas. They are not starting prices or quotations for an identified unit. The 98 three-bedroom and 78 four-bedroom townhouses total 176 homes; attached variants total 134, alongside 47 garden villas.
The plot schedule contains 46 waterfront and 14 beachfront parcels. Plots are land purchases; the illustrated mansion is not included. Controls include B+G+2, FAR 0.97 and a 12.5 m height limit. NSA for homes and GFA for plots are different measures.
Pools and landscaping are to be provided by the end user. That affects what the buyer receives even when the brochure image presents a completed lifestyle setting.
Sources for The offering+
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
09The relative advantage
Where Island E has the stronger proposition.
| Decision factor | Island E advantage | Established peer advantage |
|---|---|---|
| Entry capital | Lower scheduled home / plot cheques | Higher prices already attach to mature settings |
| Community planning | New coordinated landscape and amenity plan | Existing facilities can be inspected and used |
| Land selection | Current scheduled coastal plot release | Completed custom homes and established plots |
| Value creation | Delivery and destination maturation ahead | Proven end-user demand and resale comparables |
| Five-year use | Suited to patient ownership into delivery | Ready occupation, rental and use where completed |
Island E’s advantage is strongest for a buyer seeking coastal land or a new family home at a lower absolute entry price, with the potential benefit of a coordinated community taking shape. It is less compelling for a buyer whose priority is immediate occupation at an already recognised trophy address.
La Mer South and Pearl Jumeirah offer closer custom-home comparisons than branded apartments. Jumeirah Bay tests the upper limit of destination prestige. Palm Jumeirah tests the value of operational maturity and an established resale audience.
The investment judgement is selective: a well-positioned Island E plot can be a more attractive use of a given capital allocation. That does not make every Island E unit superior to every villa in these established communities.
Sources for The relative advantage+
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
- Dubai Sotheby’s · AED330M Jumeirah Bay villa sale ↗
- Sotheby’s · La Mer South four-bedroom villa ↗
- Owner listing · Pearl Jumeirah corner plot PJ-012 ↗
10The 2026–2031 thesis
Buy the future benefit at a disciplined entry price.
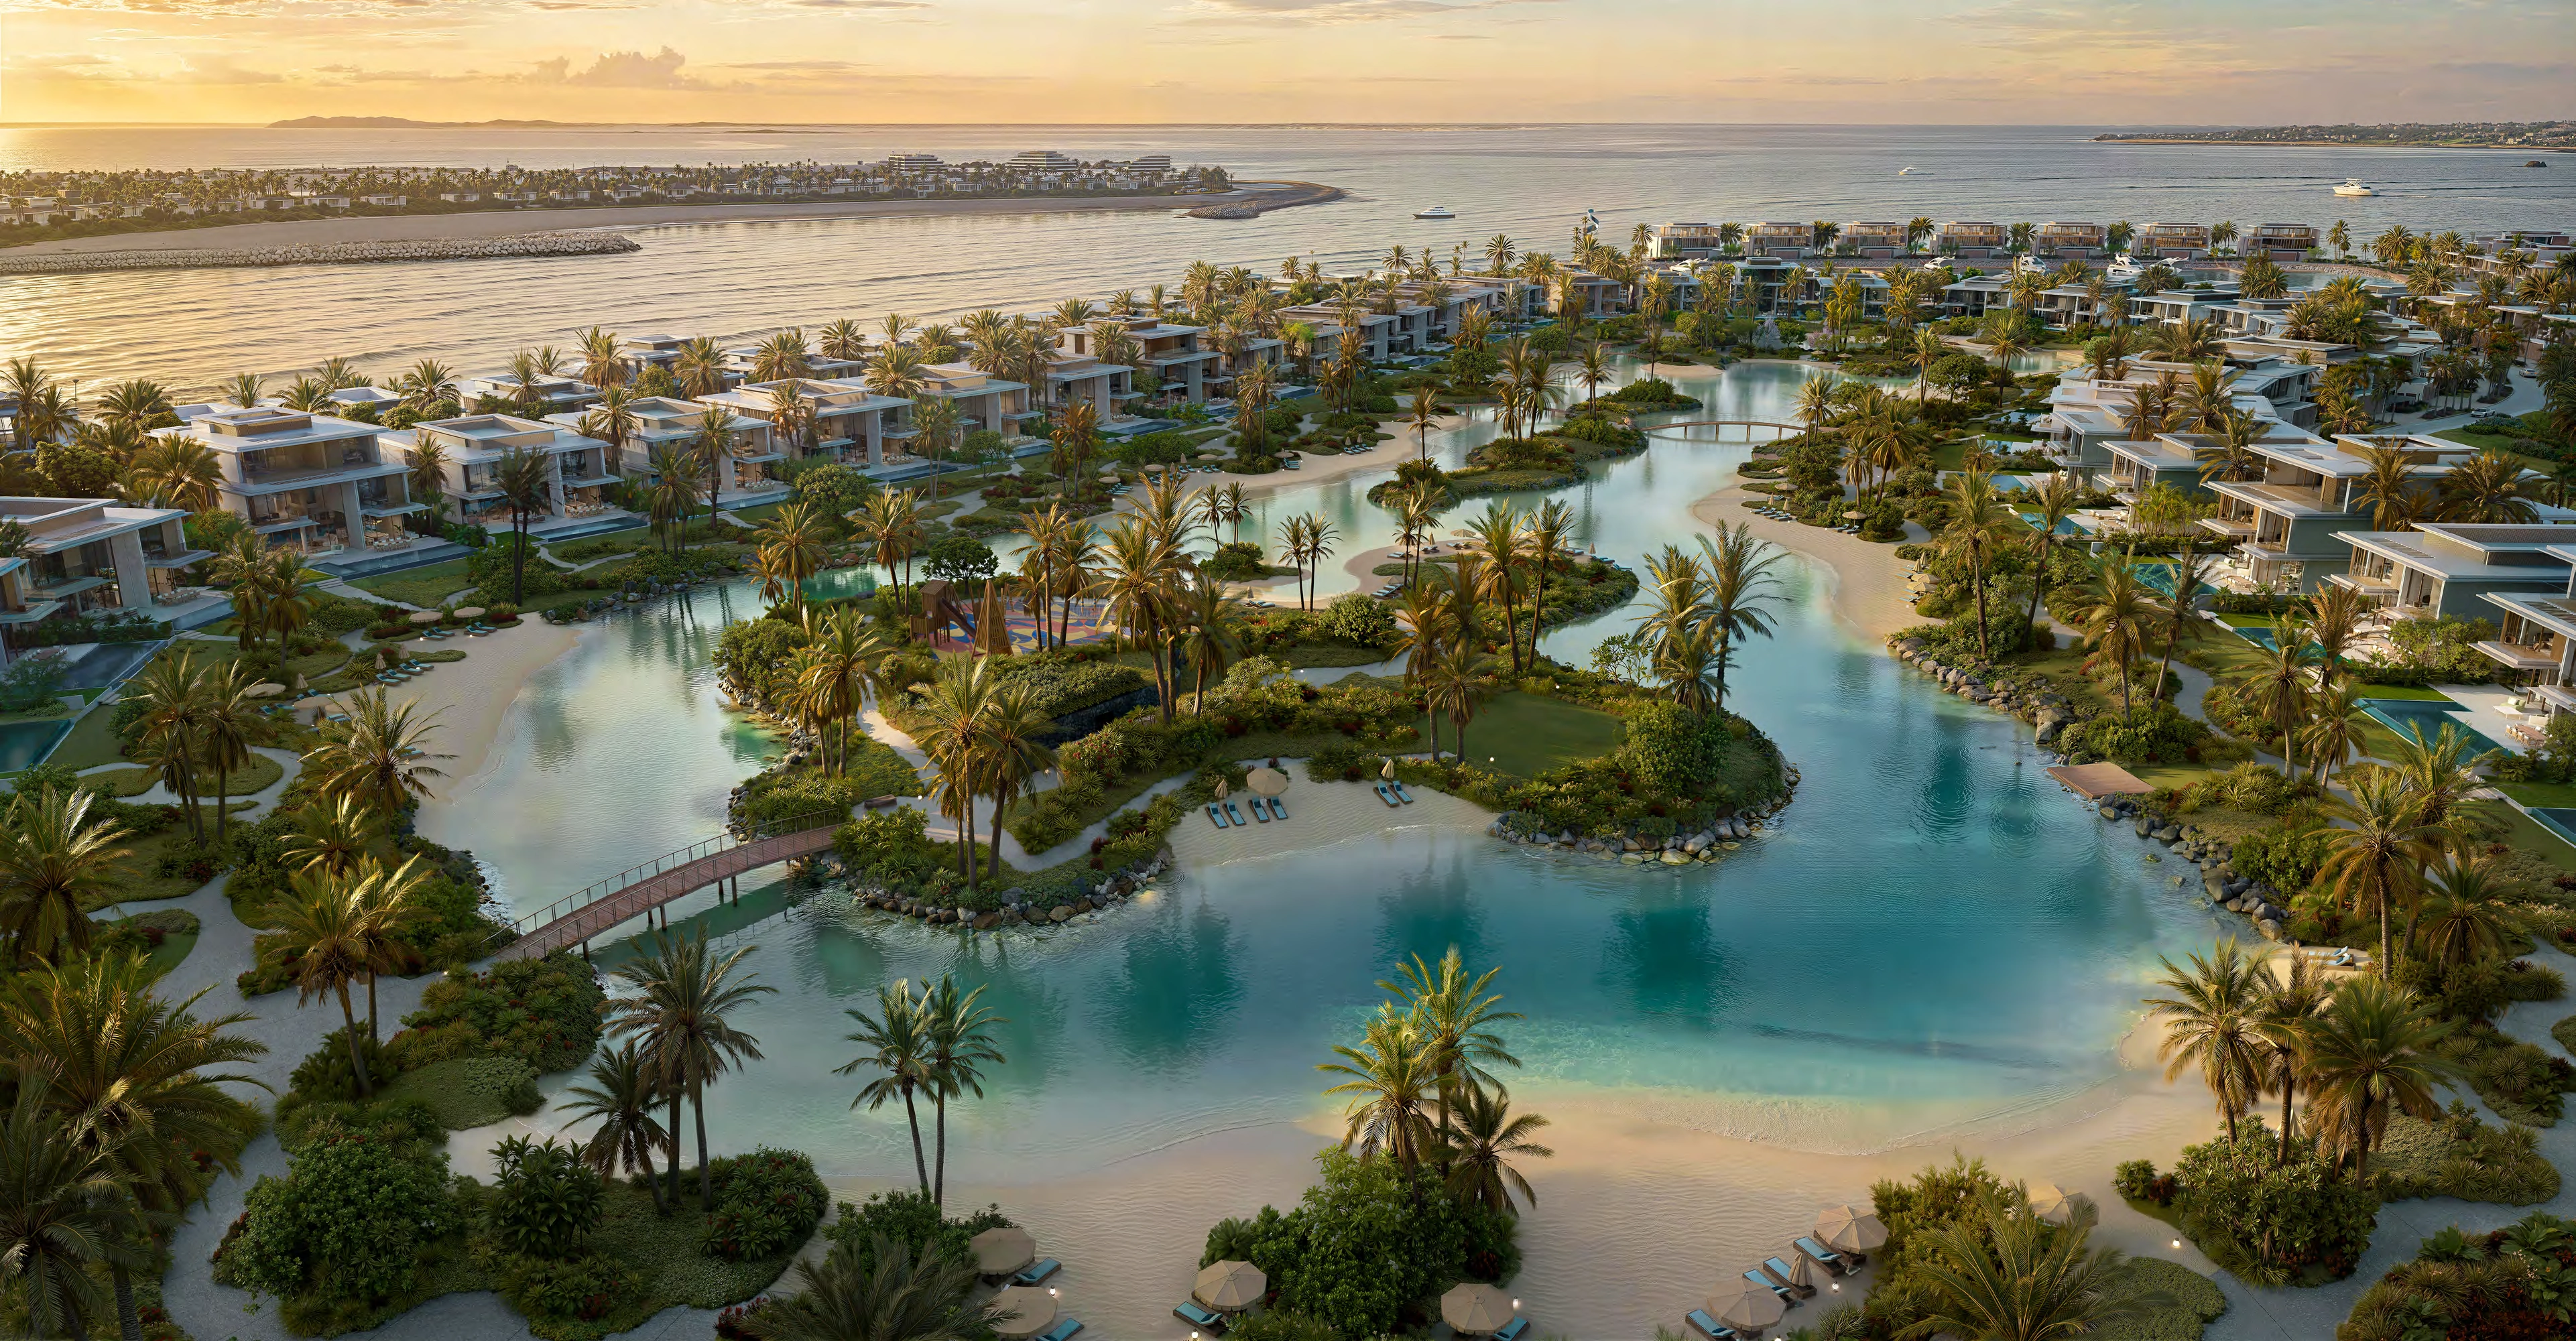
Three developments could support repricing: reliable access and infrastructure; usable beaches, lagoons and community facilities; and occupation that turns a brochure setting into an address people choose to live in. Each can reduce the difference between an unfinished project and a mature substitute.
For a plot, the strongest driver is the land position: frontage, orientation, privacy, permitted floor area and neighbouring uses. A buyer building a residence must assess the total completed-home cost separately. For a developer-built villa, layout, specification and usable space carry more of the comparison.
The comparison should be refreshed as delivery progresses: actual releases and resales on Island E, availability of comparable coastal land, completed-home demand and the timetable of the dedicated access and amenities. A cheaper initial purchase is valuable only if the eventual home remains competitive.
IWR conclusion: Island E is a credible earlier-stage alternative to Dubai’s established coastal enclaves. Its appeal is the combination of land choice, a lower entry cheque and planned community quality. Historical appreciation shows what scarcity and maturity have achieved elsewhere; it does not supply an automatic five-year return target for Bay Estate.
Sources for The 2026–2031 thesis+
- Nakheel · Bay Estate Project Briefing · supplied official material, October 2026
- ValuStrat · August 2026 market reading ↗
Sources & dates 14 references / 1 October 2026+
- Nakheel · Bay Estate Project Briefing
Supplied official briefing, extracted 1 October 2026. Inventory p.16; average price/area schedules pp.71–72. Brochures and plot controls retained in the Bay Estate source library.
- Knight Frank · US$10M+ sales, Q4 2025 ↗
12 January 2026. Prime residential values +194% from Q4 2020 through Q4 2025; broad prime basket, not a separate island index.
- ValuStrat · Dubai Q1 2026 report ↗
Report pp.6–7: villa index 306.6; prime villas 334.3; January 2021=100. Palm villas described as approximately fourfold from the 2021 trough. Public report copy: https://manuals.plus/m/b8d2f3efb2195e620bf33ec0614b6522f0ebfe42d7249c53e90e7e6c7ba74896
- ValuStrat · August 2026 market reading ↗
22 September 2026. Dubai villa values −1.7% year-on-year in August; broad index, not Island E.
- Knight Frank · Destination Dubai 2025 ↗
Jumeirah Bay 24,500 sq ft plot sold for AED125M in April 2023; approximately AED5,100 per plot sq ft.
- Bloomberg / The Business Times · Jumeirah Bay plot resale ↗
2023 reporting cites DLD purchase at AED36.5M in 2021 and AED125M resale in 2023. One same-plot example; gross gain before costs; not five years.
- Dubai Sotheby’s · AED330M Jumeirah Bay villa sale ↗
Broker-reported completed sale, March 2025. Custom villa on one of three tip plots; 26,895 sq ft plot. Not a standard villa average.
- Sotheby’s · La Mer South four-bedroom villa ↗
Observed 1 October 2026. AED60M asking price; 9,707 sq ft interior / 7,226 sq ft plot. Listing, not a closed sale.
- Sotheby’s · Pearl Jumeirah seven-bedroom mansion ↗
Search-indexed asking price AED50M, observed 1 October 2026. Direct page intermittently unavailable; corroboration below supports the island’s active luxury-villa market, not this asking price as a sale.
- Atara · Pearl Jumeirah H1 2026 villa sales ↗
Developer reports AED110M aggregate H1 2026 villa sales; no per-home return inferred.
- Owner listing · Pearl Jumeirah corner plot PJ-012 ↗
Updated 29 September 2026: AED29.35M ask; 11,751 sq ft portal / 11,750 description. Uses portal area; corner plot, no established direct-beach frontage.
- Gulf News · La Mer South land listings ↗
2025 dated asking-price context: AED29–30M smaller plot listings and AED160M trophy parcel; not current October 2026 valuations or achieved sales.
- Nakheel · Dubai Islands masterplan ↗
Five islands, 17 sq km, over 20 km of beaches and around 2 sq km of parks/open space. Masterplan quantities, not delivered inventory.
- Dubai Media Office · Al Mamzar beaches development ↗
21 April 2026 progress announcement: AED500M public beach development.
USD equivalents use 3.6725 AED/USD. Historical appreciation excludes income and costs. Comparative judgements are IWR analysis.